
Before we get into the meat of this morning’s edition buying these “price slam dips” is highly lucrative (in my view)
Don’t Miss It: Three Silver Miners on the Edge of Ignition
Aya Gold & Silver (OTC: AYASF) is the emerging flagship of this new silver regime. Its Zgounder mine in Morocco just posted record 2025 production of about 4.83 million ounces of silver, nearly triple 2024, capped by a monster Q4 with 1.37 million ounces and a record 545,491‑ounce December as the expanded plant ran above nameplate capacity. With Boumadine advancing behind it and a supportive mining jurisdiction, Aya is quietly transforming into a multi‑asset primary silver producer feeding a market where physical is already clearing at three‑digit prices in the East.
Andean Precious Metals (OTC: ANPMF) offers a very different but equally powerful angle: it operates the San Bartolomé plant in Bolivia, the country’s dominant silver oxide processing hub, sourcing ore from a vast network of artisanal and cooperative miners instead of relying on a single nationalization‑risk deposit. Its sliding‑scale payment model means feed costs flex with metal prices, crushing downside margin risk while preserving enormous upside torque when silver rips higher, and Bolivia’s prior nationalizations actually entrench Andean as the indispensable mid‑stream processor for the district’s remaining silver inventory.
Kuya Silver (OTC: KUYAF) is the high‑beta newcomer ramping into this squeeze. The company has brought the historic Bethania mine in Peru back into production, reporting record concentrate sales in 2025 as throughput, grades, and recoveries improved quarter after quarter. In Q3‑2025, Bethania generated roughly 16,983 ounces of silver (over 21,000 oz silver‑equivalent) with recoveries above 91% and about 79% of revenue coming from silver, and management is targeting higher tonnage and further optimization through 2026 as new infrastructure and drilling unlock more of the vein system.
The key takeaway in the Kuya Silver story is that the company is only just getting started. Kuya is advancing its deposit from a discovery phase into full production—and is on track to increase its quarterly silver output by 20x before the end of this year.
SILVER MANIFESTO: THE SYSTEM IS ALREADY BROKEN
The Squeeze They Can’t Admit
The ongoing squeeze in above‑ground, globally refined physical silver is now the central fact of this market, not a fringe thesis. Retail investors are marginal; the real accumulation is coming from nation‑states, sovereign entities, and industrial proxies quietly draining available stockpiles.
What remains is a scramble for leftovers among smaller industrials and retail buyers who are competing over whatever slips past state and strategic hoarders. Anyone denying this is either uninformed, misled, or actively running cover for a system that depends on the public staying trapped in paper promises.
The Short That Cannot Escape
-
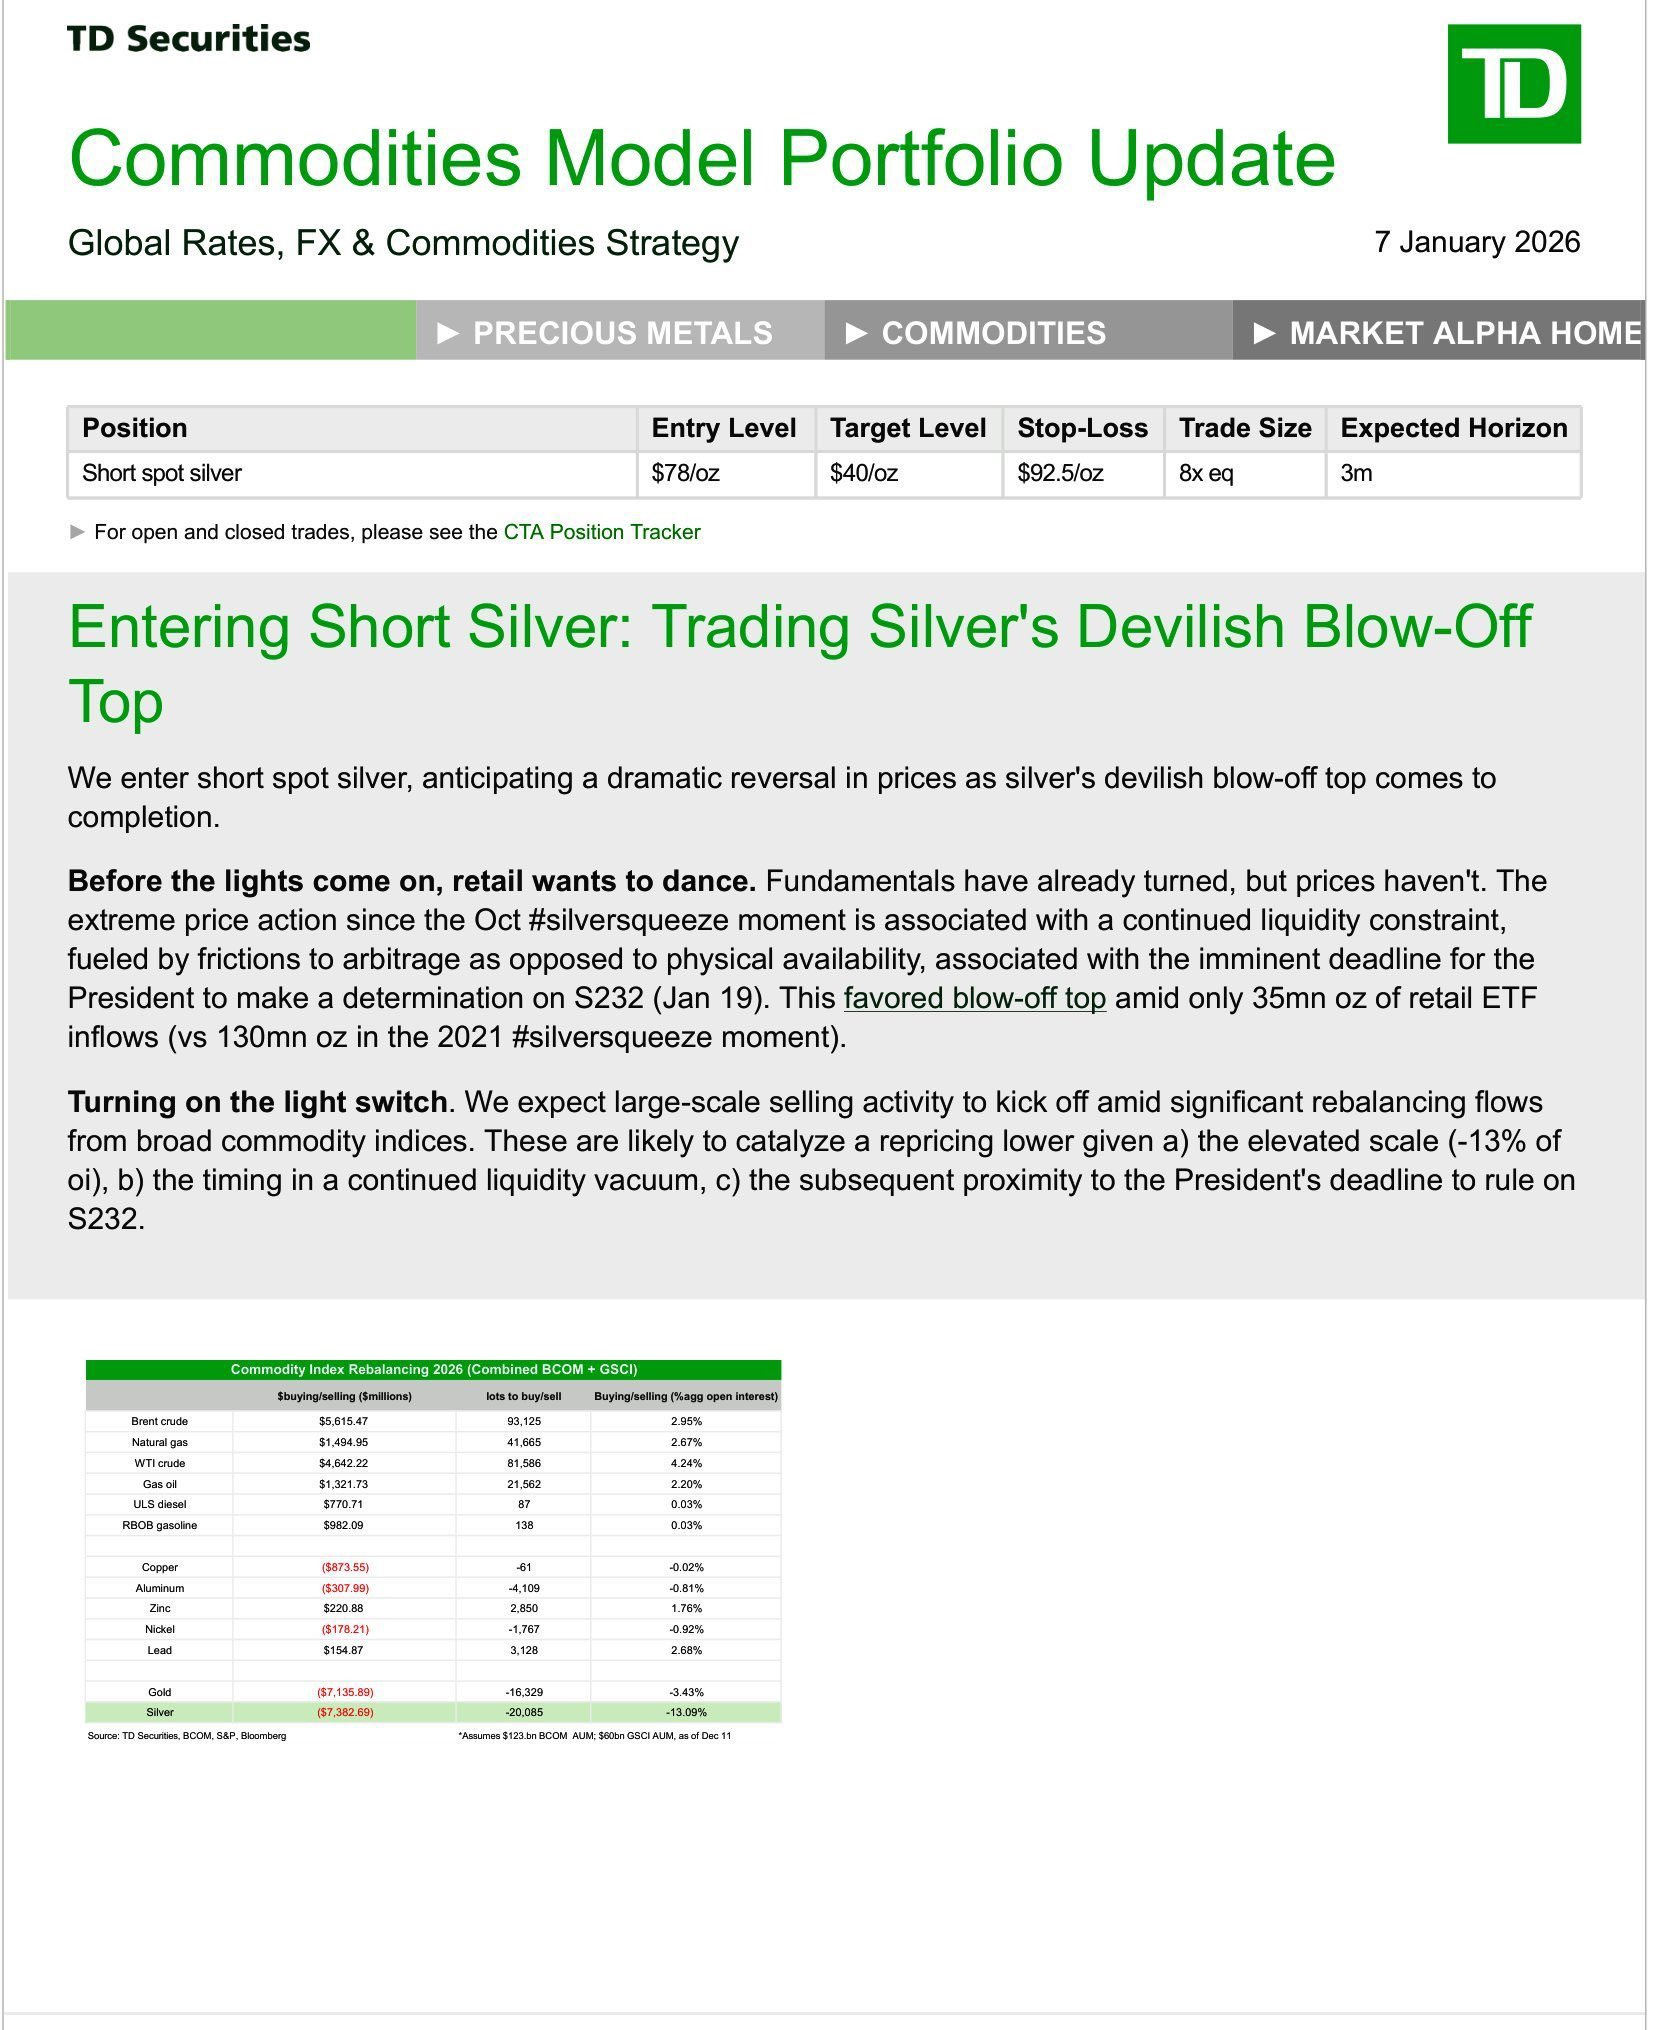
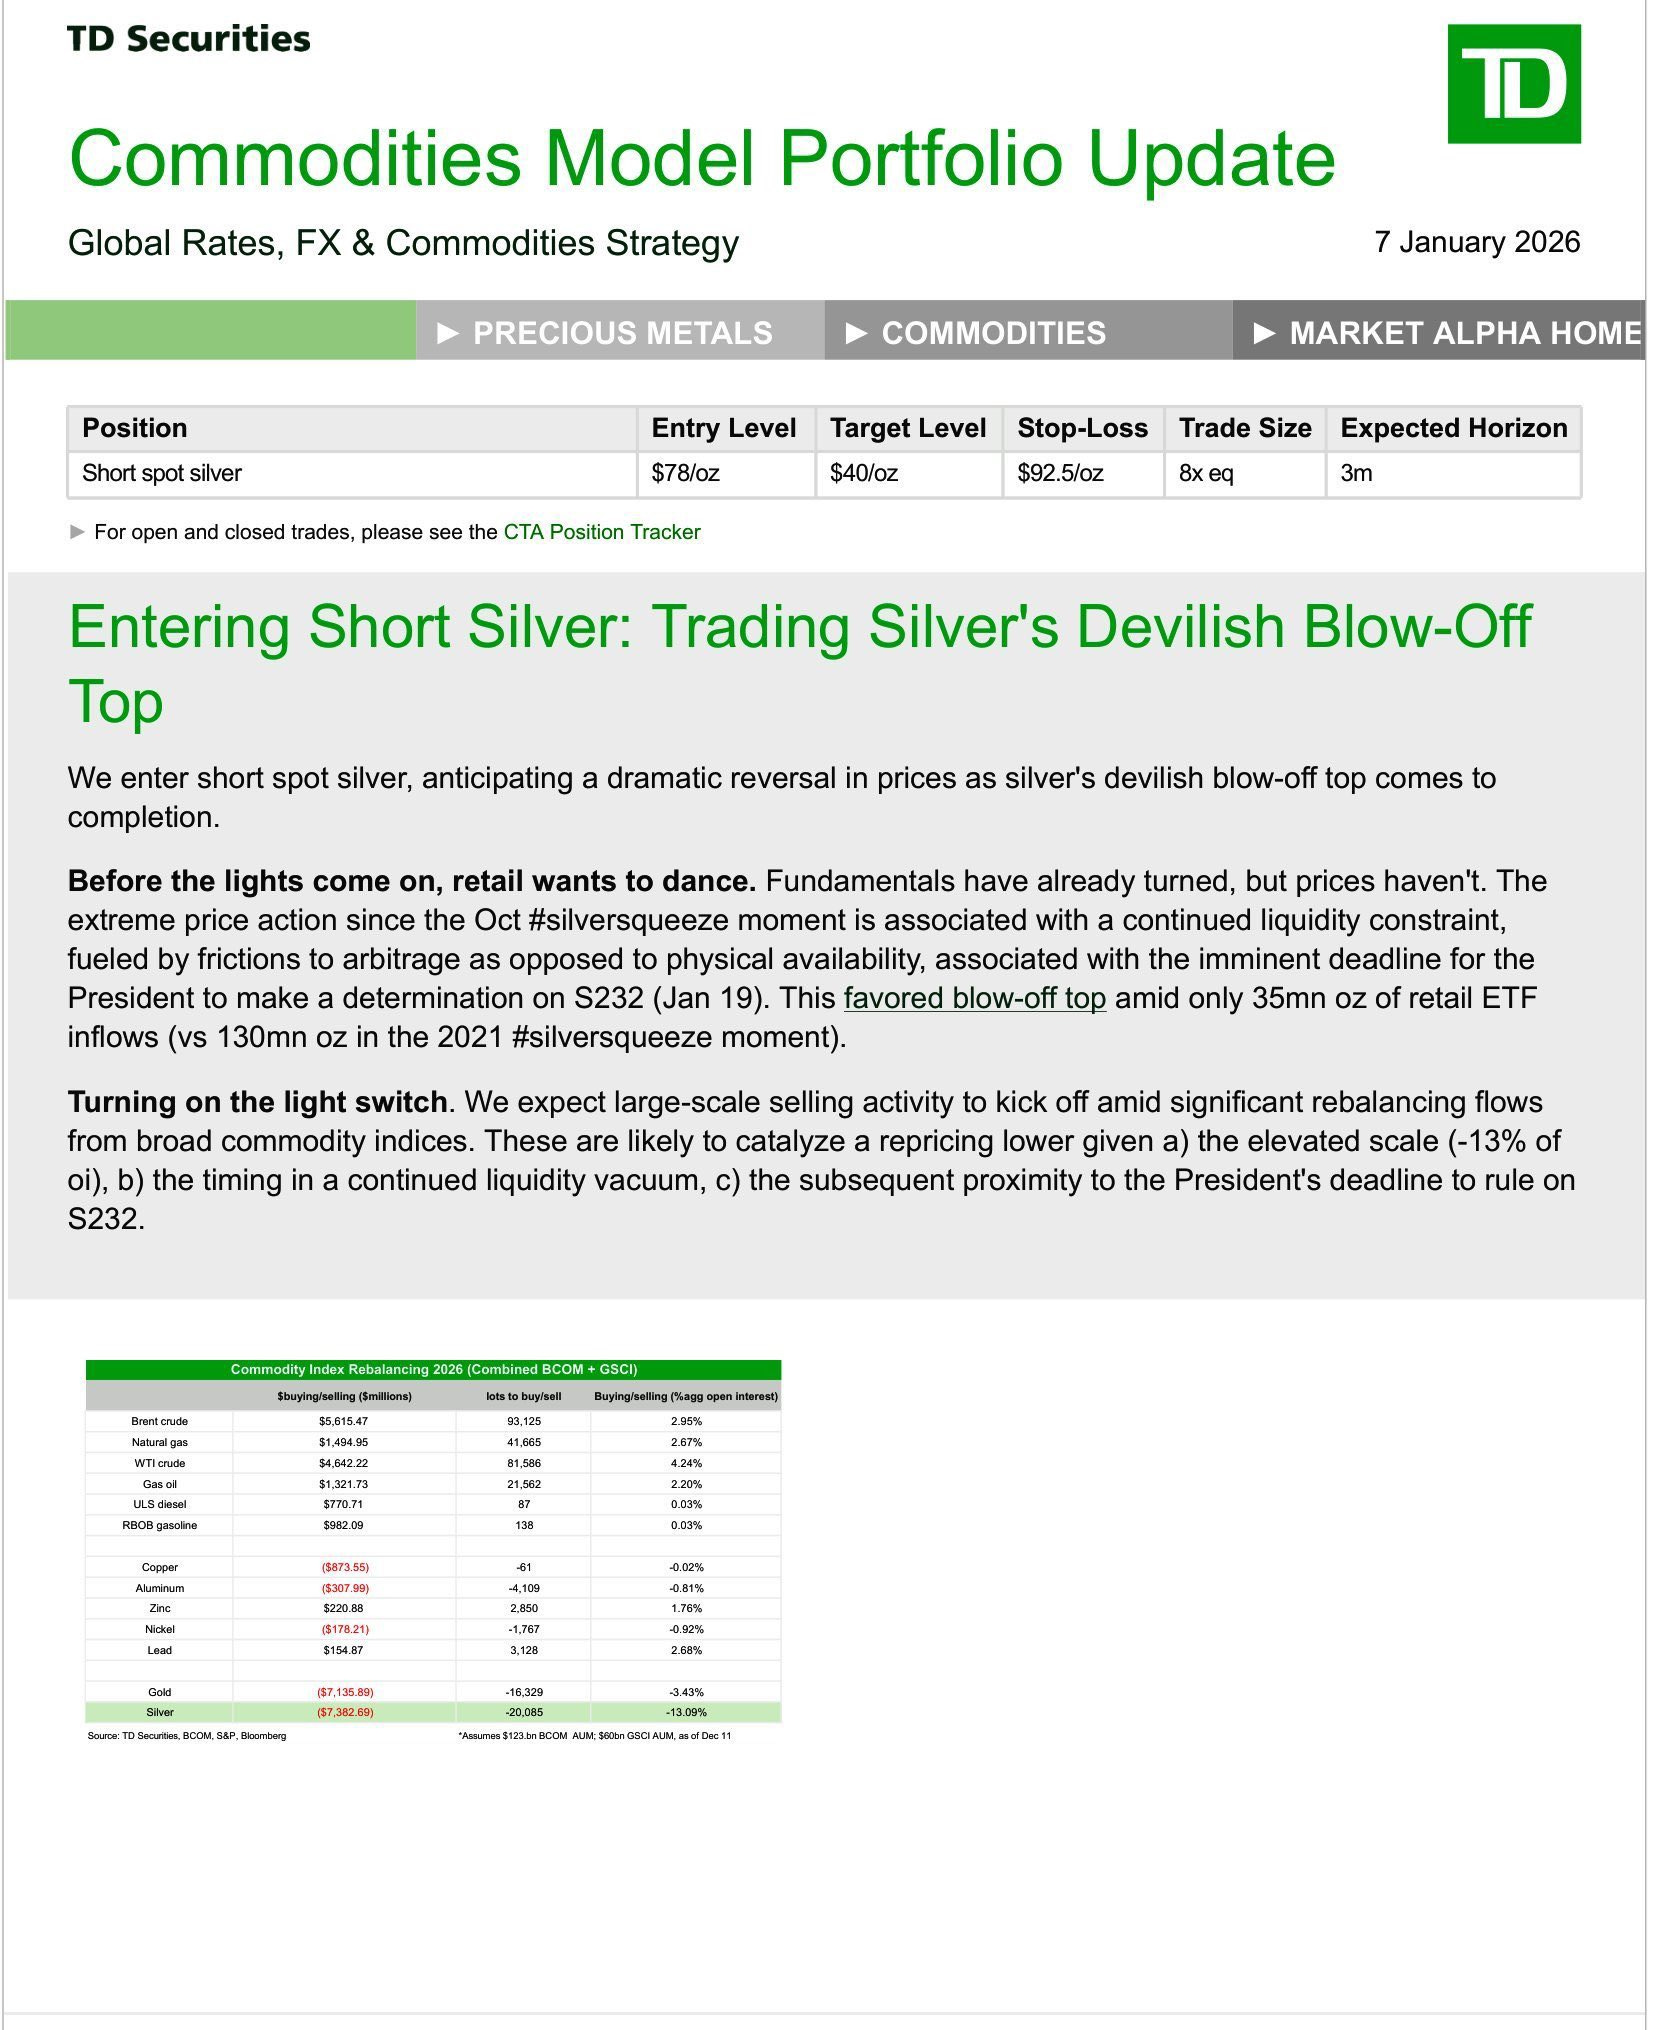
The Canadian bank TD Securities tried shorting silver
-
betting Silver would go to $40
-
with a time horizon of 3 months.
-
One week later: liquidated
-
They called it the ‘devilish blow-off top’
-
In an environment where Silver is rising amid supply demand fundamentals the short selling suppression will lose every single time.
-
This is why JP Morgan (once a serial short seller themselves ) flipped to a long position
Global banks are short billions of dollars’ worth of silver in a market already running long‑term structural deficits. Industrial demand consumes the majority of annual supply before a single ounce reaches investment channels, leaving no surplus for orderly short‑covering.
To fully cover, these institutions would need years of total global mine output in a world where every incremental ounce is pre‑claimed by solar, electronics, AI hardware, EVs, 5G, robotics, electric trains, batteries, data centers, aerospace, and defense. Every attempt to buy back metal drives prices higher, which makes remaining positions more expensive, creating a self‑reinforcing doom loop.
When China Turns Off the Spigot
China now dominates the refining chokepoint, handling an estimated 60–70% of globally processed, tradeable silver. Through export controls, licensing rules, and tighter oversight, it has effectively told the world, “No silver unless it serves Chinese priorities first.”
Layered on top of that is a Chinese M2 money supply exceeding 45 trillion dollars, larger than the U.S. and Eurozone combined, pouring liquidity into a finite pool of hard assets. That combination—monetary expansion plus chokepoint control over refining—sets the stage for a commodity supercycle with silver in the blast radius.
Gold Blinks First, Silver Strikes Next
Global central banks have already made their move, loading up on gold and reducing U.S. dollar exposure at the fastest pace in modern history. Gold has quietly broken out against major equity indices, signaling that fiat‑denominated paper wealth is losing its grip on reality.
Now silver is starting to outperform gold, forcing the stretched gold‑to‑silver ratio to mean‑revert toward its historic zone near 15:1. With a conservative 4,500‑dollar gold price implied by ongoing central‑bank buying and macro stress, a 300‑dollar silver price is not a moonshot; it is simple ratio arithmetic.
From Industrial Input to Monetary Weapon
Silver is the highest‑conductivity metal at the core of every growth driver: solar, AI, 5G, EVs, data centers, robotics, aerospace, and defense systems. Solar alone already consumes a fifth or more of annual supply and is still gaining share as grids decarbonize and compute loads explode.
In an environment of inflation, geopolitical fracture, de‑dollarization, and systemic financial risk, silver is reasserting itself as a monetary metal with a far smaller market and tighter supply than gold. The 50‑year cup‑and‑handle is not just a chart pattern—it is the visual signature of silver repricing into a world where physical holders dictate terms and paper believers learn what “no offer” really means
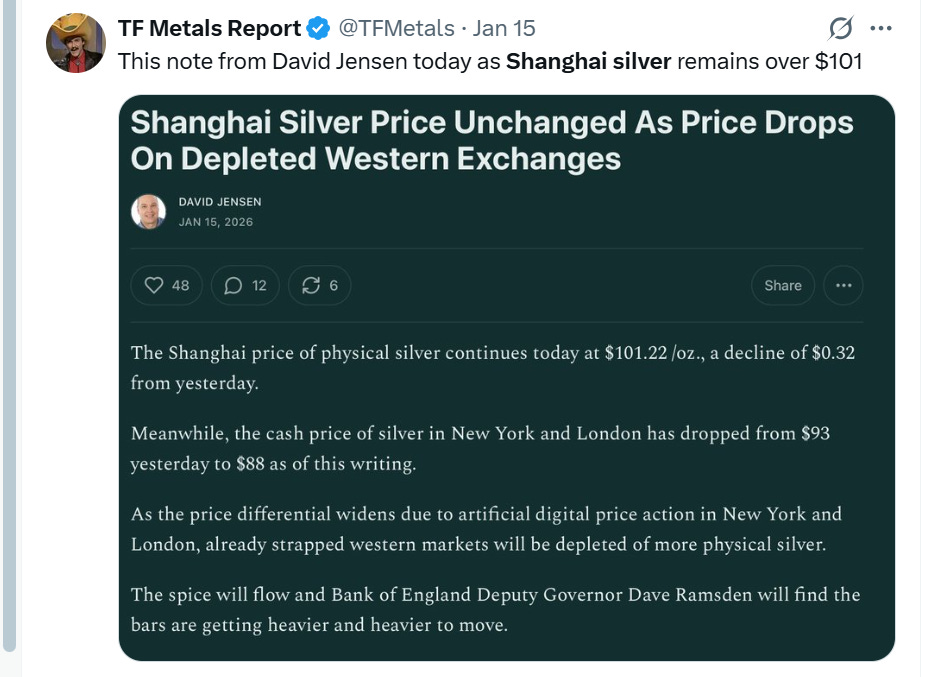
Shanghai Silver holding over $101
A whopping $13 over Crimex Comex spot price
-
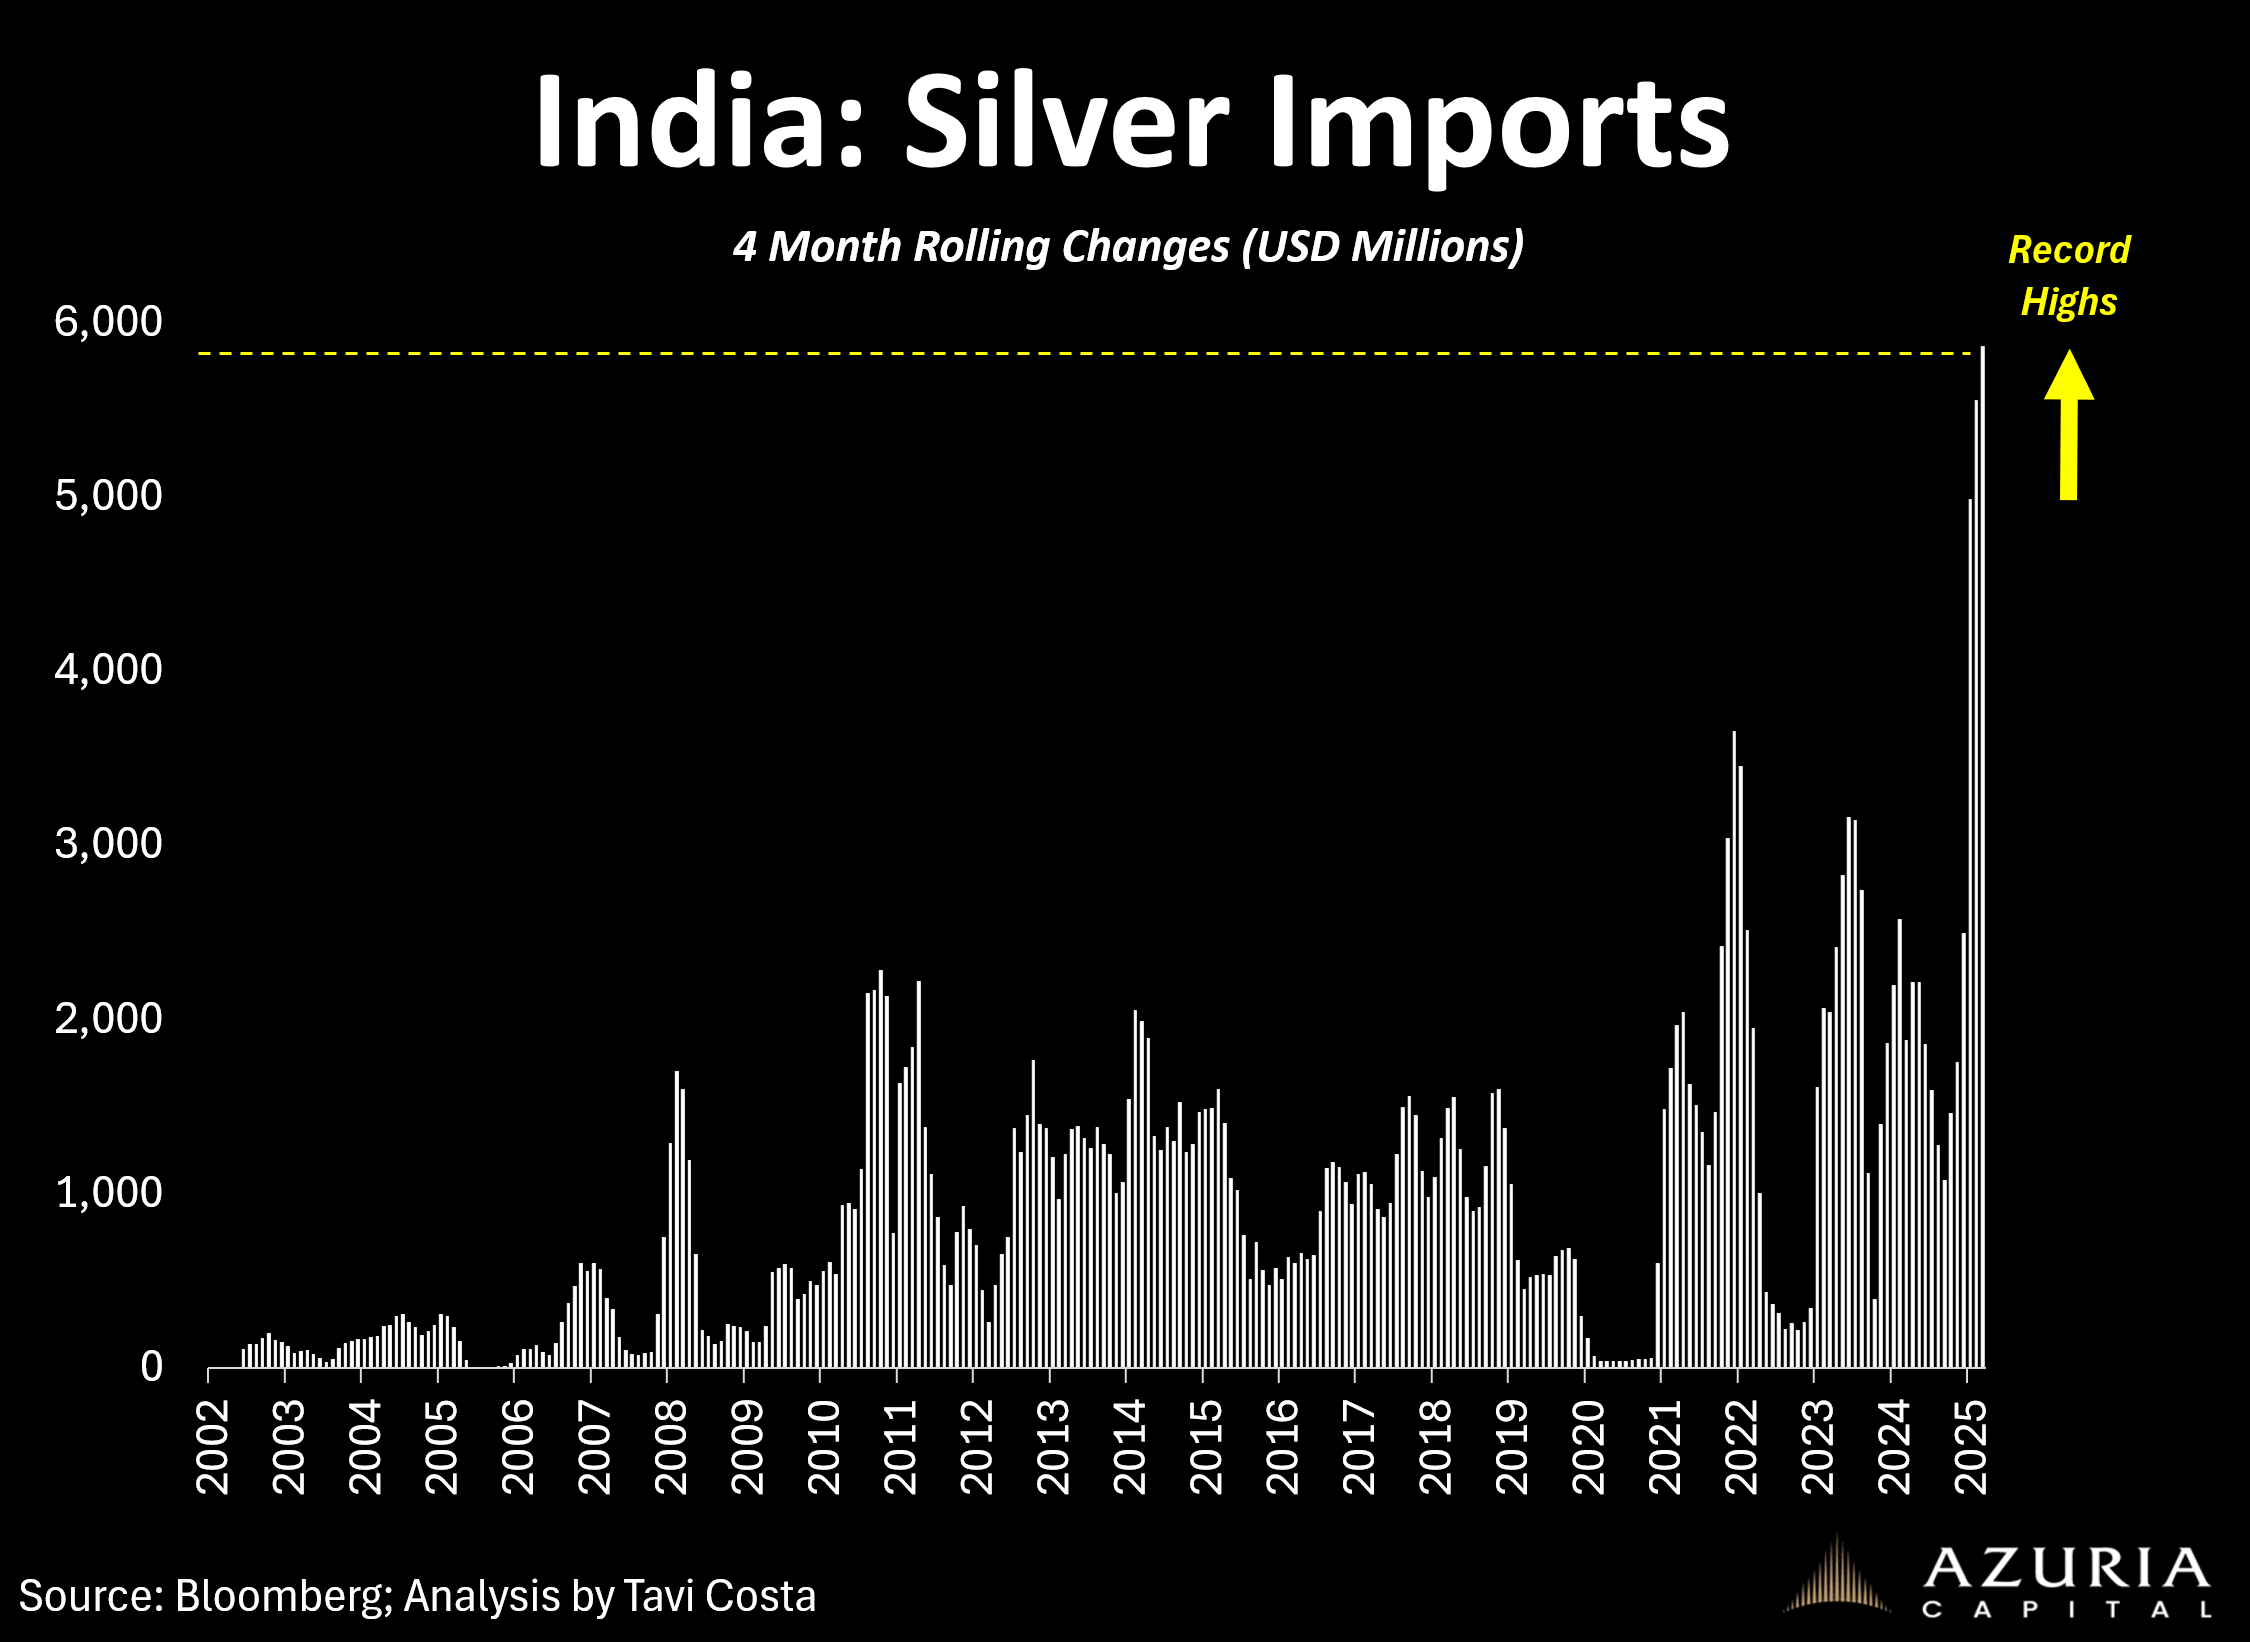
Later today we unpack this chart below on India’s Silver imports. Hat tip goes to our colleague Tavi Costa.
-
We ran some numbers on how many people have been added to India’s middle class amid all the US outsourcing over past 50 years.
-
The numbers will blow your mind
-
and this afternoon’s post is bigger bullish silver news than all the editorial written above (in terms of silver demand, BY FAR)
-
Recall it is when Silver is valued monetarily that we see the big runs
-
Thus, the Silver bull ran doesn’t start until April 2026 when the new bank loan rules in India kick in.
-
What we are seeing now is merely what is called “foreplay”
end of segment
-
our opinions are not our sponsors opinions
-
the editorial department is separate from the promotions department
-
not financial advice