
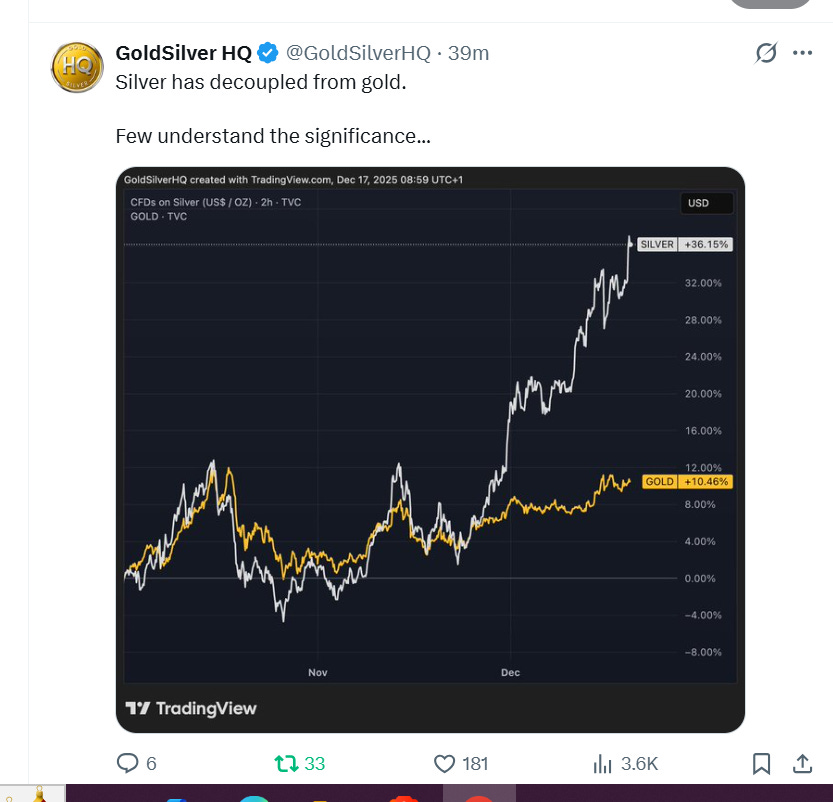
Two enormous signals just lit up the precious metals universe at the same time: gold has broken out against the S&P 500, and silver has broken out against gold. This is not late-stage froth – it is early-phase liftoff for what could be the most explosive silver bull market in history.
Gold leaves the S&P in the dust
For over a decade, gold has quietly been building a massive 10–11 year base versus the S&P 500, oscillating in a tight spread while Wall Street worshipped AI, tech and index funds. That base has finally detonated. November’s monthly close saw gold’s performance ratio versus the S&P punch clean through multi-year resistance on the spread chart – the kind of structural breakout that says “multi-year asset rotation,” not “nice little rally.” Gold has already broken out versus the Dow and NYSE Composite, and now the last holdout – the S&P 500, stuffed with AI darlings – is losing the duel as capital begins to quietly slip from overowned equities into monetary metal. When a base that wide and that deep resolves higher, you are not pricing in a month or two of strength; you are launching a multi-year trend.
Silver breaks out from gold
But here’s where the story turns from bullish to outright insane: even as gold is declaring victory over the S&P, silver is breaking out from underneath gold itself. The silver–gold spread, which had languished for years after 2020, has just blasted out of a multi-year base, signaling that silver is set to outpace the “mama metal.” Silver has ripped to fresh all‑time highs near 64–66 dollars, up around 120% year‑on‑year – roughly double gold’s already stunning 60‑plus percent gain – as the silver–gold ratio compresses and momentum surges into the white metal. This is exactly what you see at the front end of a parabolic phase: the junior monetary metal seizes leadership from gold and starts to trade like it is strapped to a rocket.
The quantum leap phase for silver
Put these two breakouts together – gold vs S&P and silver vs gold – and you have a two‑stage ignition sequence pointing to a “quantum leap” repricing in silver, not a slow grind. Gold’s 10–11 year base versus financial assets is just now resolving higher, which historically implies years of outperformance as money flees overvalued paper into hard assets. Silver, with a far smaller and tighter market than gold, is already moving faster, with multiple technical analyses flagging that a decisive break over prior highs opens a legitimate runway toward triple‑digit pricing in coming quarters, not decades, as the ratio to gold normalizes and speculative plus institutional capital piles in. In other words: this is the early innings of the silver move, not the top – the point in the movie where the lights flicker, the crowd senses something big is coming, and the exits are still miraculously open.
2025
Silver +124%
Platinum +104%
Palladium +76%
Gold +63%
Copper +29%
VS
Silver miners industry wide : +139%
LOOK at this Chart and when you look at it it spells Massive Gains if you position today
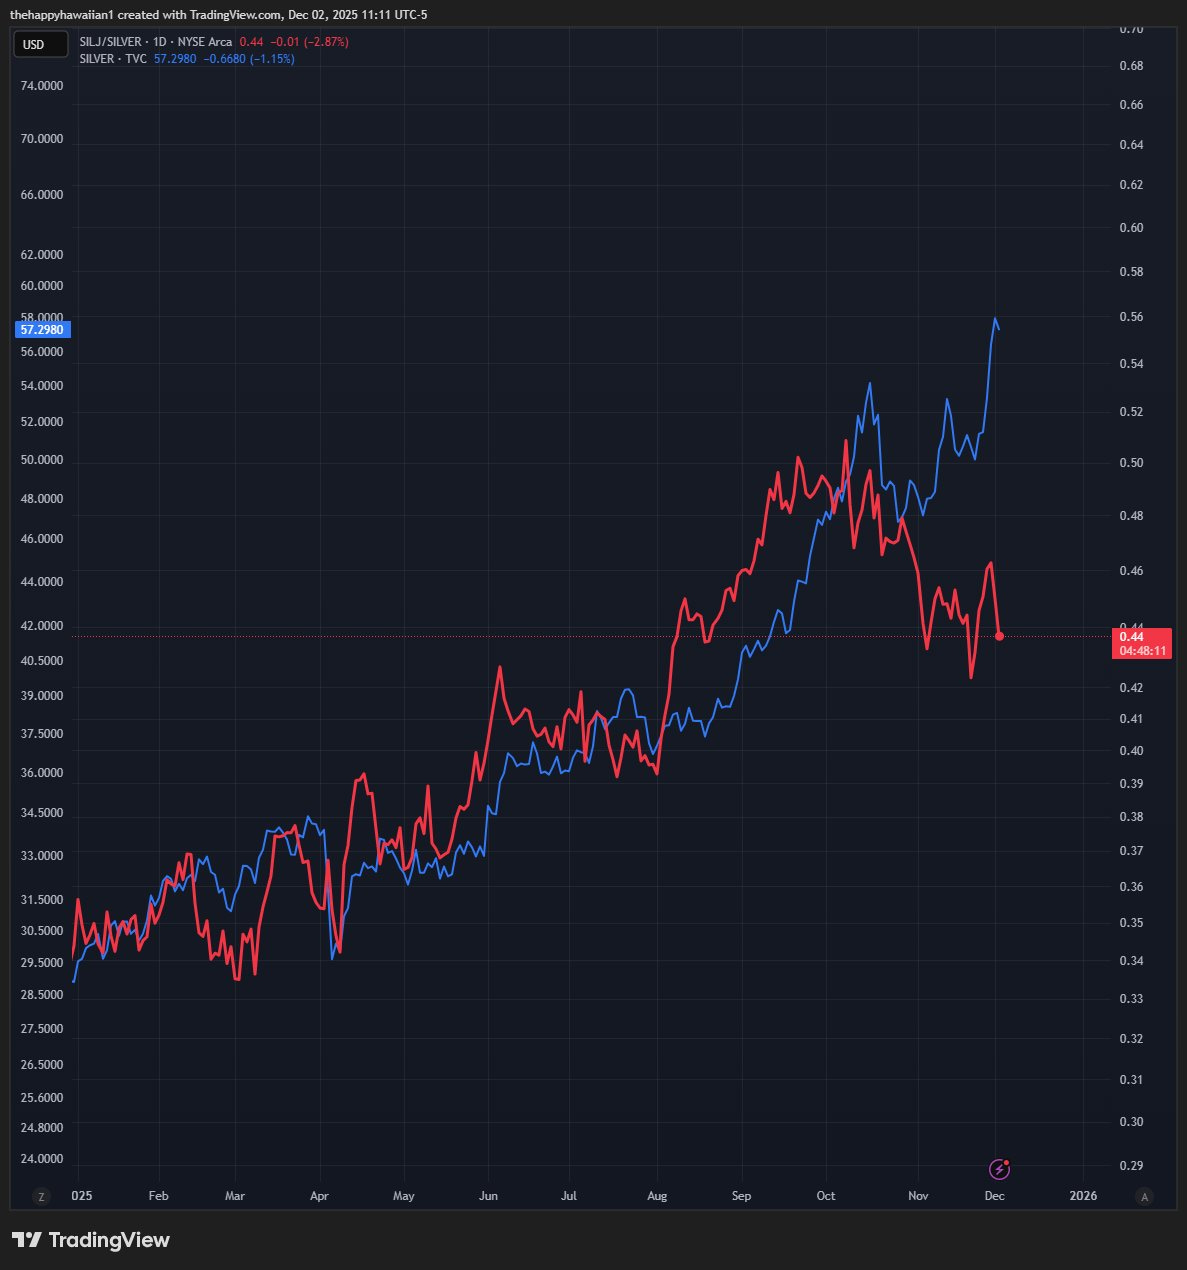
On the chart, the blue line shows silver prices in 2025. The red line represents the SILJ-to-silver ratio. The gap between them has exploded this past month meaning Silver miners are about to explode to the upside to close up this massive divergence. This is true even if Silver didn’t go higher that todays price
The market still hasn’t woken up to silver miners — Wall Street remains asleep. Yet, as Michael Hartnett puts it, we’re stepping into the “era of commodities.” Fiat currencies are visibly failing, and real assets — tangible resources like silver — are becoming the new form of money.
We’re also entering a world that’s moving away from “just-in-time” globalization. Nations are turning inward, protecting resources, restricting exports, and labeling strategic metals like silver as critical.
Silver miners are the most undervalued sectors in the market today.
In this era of commodities, where fiat is failing and nations are hoarding critical metals, pure silver miners are the ultimate asymmetric play. Three pure-play silver producers stand out: AYA Gold & Silver (AYASF), Andean Precious Metals (ANPMF), and Kuya Silver (KUYAF). All are silver-only, with no base metal exposure, and all operate in tier‑1 jurisdictions, making them ideal proxies for silver as real money in a world of debt and debasement.
AYA Gold & Silver (AYASF) runs Morocco’s second-largest silver mine, Zgounder, and is expanding into a major, low-cost producer. It’s a simple, high-grade silver story in a stable mining jurisdiction, perfectly positioned to benefit from rising silver prices and tighter supply.
Andean Precious Metals (ANPMF) operates Bolivia’s largest silver oxide plant at San Bartolomé, processing oxide ore into silver doré under a long-term agreement with Bolivia’s state miner. This is a pure silver tolling play with a large, long-life feed source in a country that treats silver as strategic.
Kuya Silver (KUYAF) is a pure silver producer in Peru, scaling up a simple, low-cost operation with no copper, lead, or zinc. It’s a clean, concentrated bet on silver as money, with a straightforward path to higher production.
Silver is in a secular bull market fueled by runaway debt, relentless currency debasement, and the irreversible breakdown of globalized supply chains — and in this environment, these three pure silver miners are massively undervalued relative to the metal itself.
Building a concentrated position in AYASF, ANPMF, and KUYAF is the most direct, powerful way to play silver’s re‑emergence as real money in the era of commodities.
But this isn’t just about money — it’s about survival. Silver is being consumed by industry at an alarming pace, critical to every major energy transition technology. This isn’t merely a great investment; it’s a necessity. Silver is the new oil, and owning these miners is how you position for the future.
Let’s just see if I’m right, here are the three tickers at time of this article being published, bookmark this.
Sprinkle in a $100,000 barbell across these 3 miners and it is predicted one will go 10X within 18 months. Perhaps all 3, it’s within the range of plausibility.
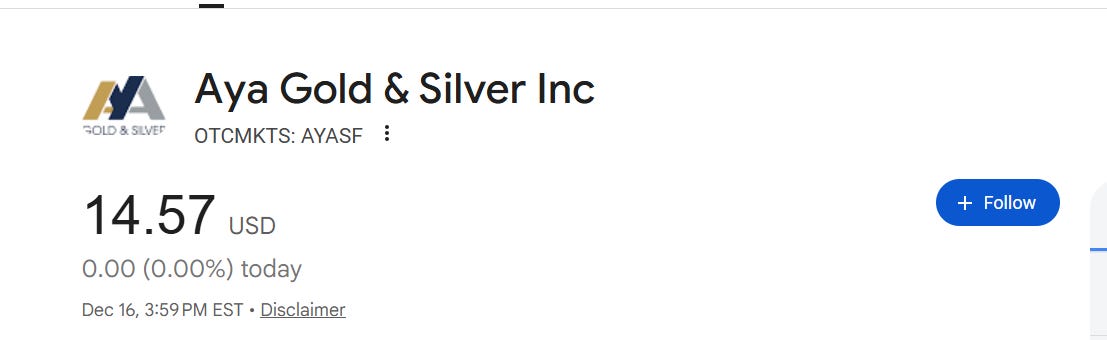
end of segment
-
our opinions are not our sponsors
-
editorial is separate from promotions
-
not financial advice