
by Jon Little intern Niko Moretti
If there has ever been a more explosive setup for silver miners, history has yet to record it. The convergence of structural supply constraints, record-shattering demand, and a wildly bullish macro environment is setting the stage for one of the biggest re-rates in modern resource investment.
Demand: The Ultimate Bull Case
Silver’s industrial demand has never been more blistering. Solar panels, EV batteries, aerospace, defense, 5G, AI, and robotics are insatiable consumers, pushing annual silver consumption to unprecedented highs. Emerging economies—especially China and India—are devouring above-ground stocks at a ferocious pace, leaving inventories perilously thin. Top analysts warn that at this rate, we could witness “no available silver” by 2026.
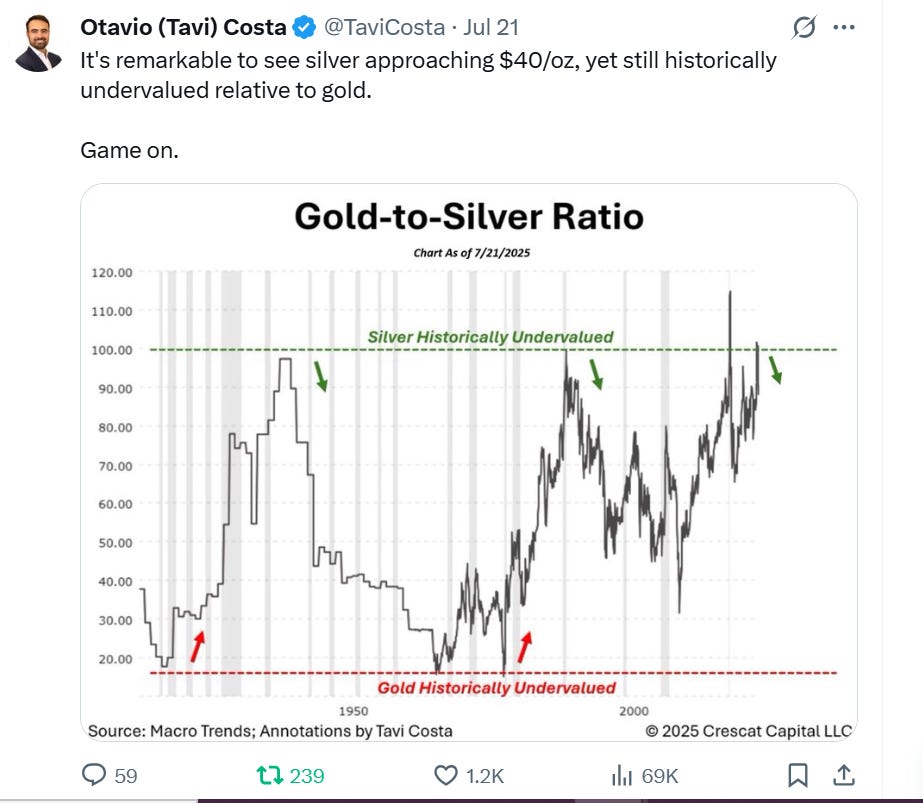
Tavi Costa puts it bluntly: “Institutional interest is starting to build, even as media coverage remains virtually nonexistent. Game on.” Jon Forrest Little captures it perfectly: “Silver has never been this undervalued compared to other equities. This is the entry point.” In his view, the supply side, long considered stable, is now facing relentless pressure—shrinking output, resource nationalism, and runaway demand. “These are structural constraints that once in place tend to last for years,” Little explains.
Supply: Falling Off a Cliff
Peak Silver is in our rear view mirror
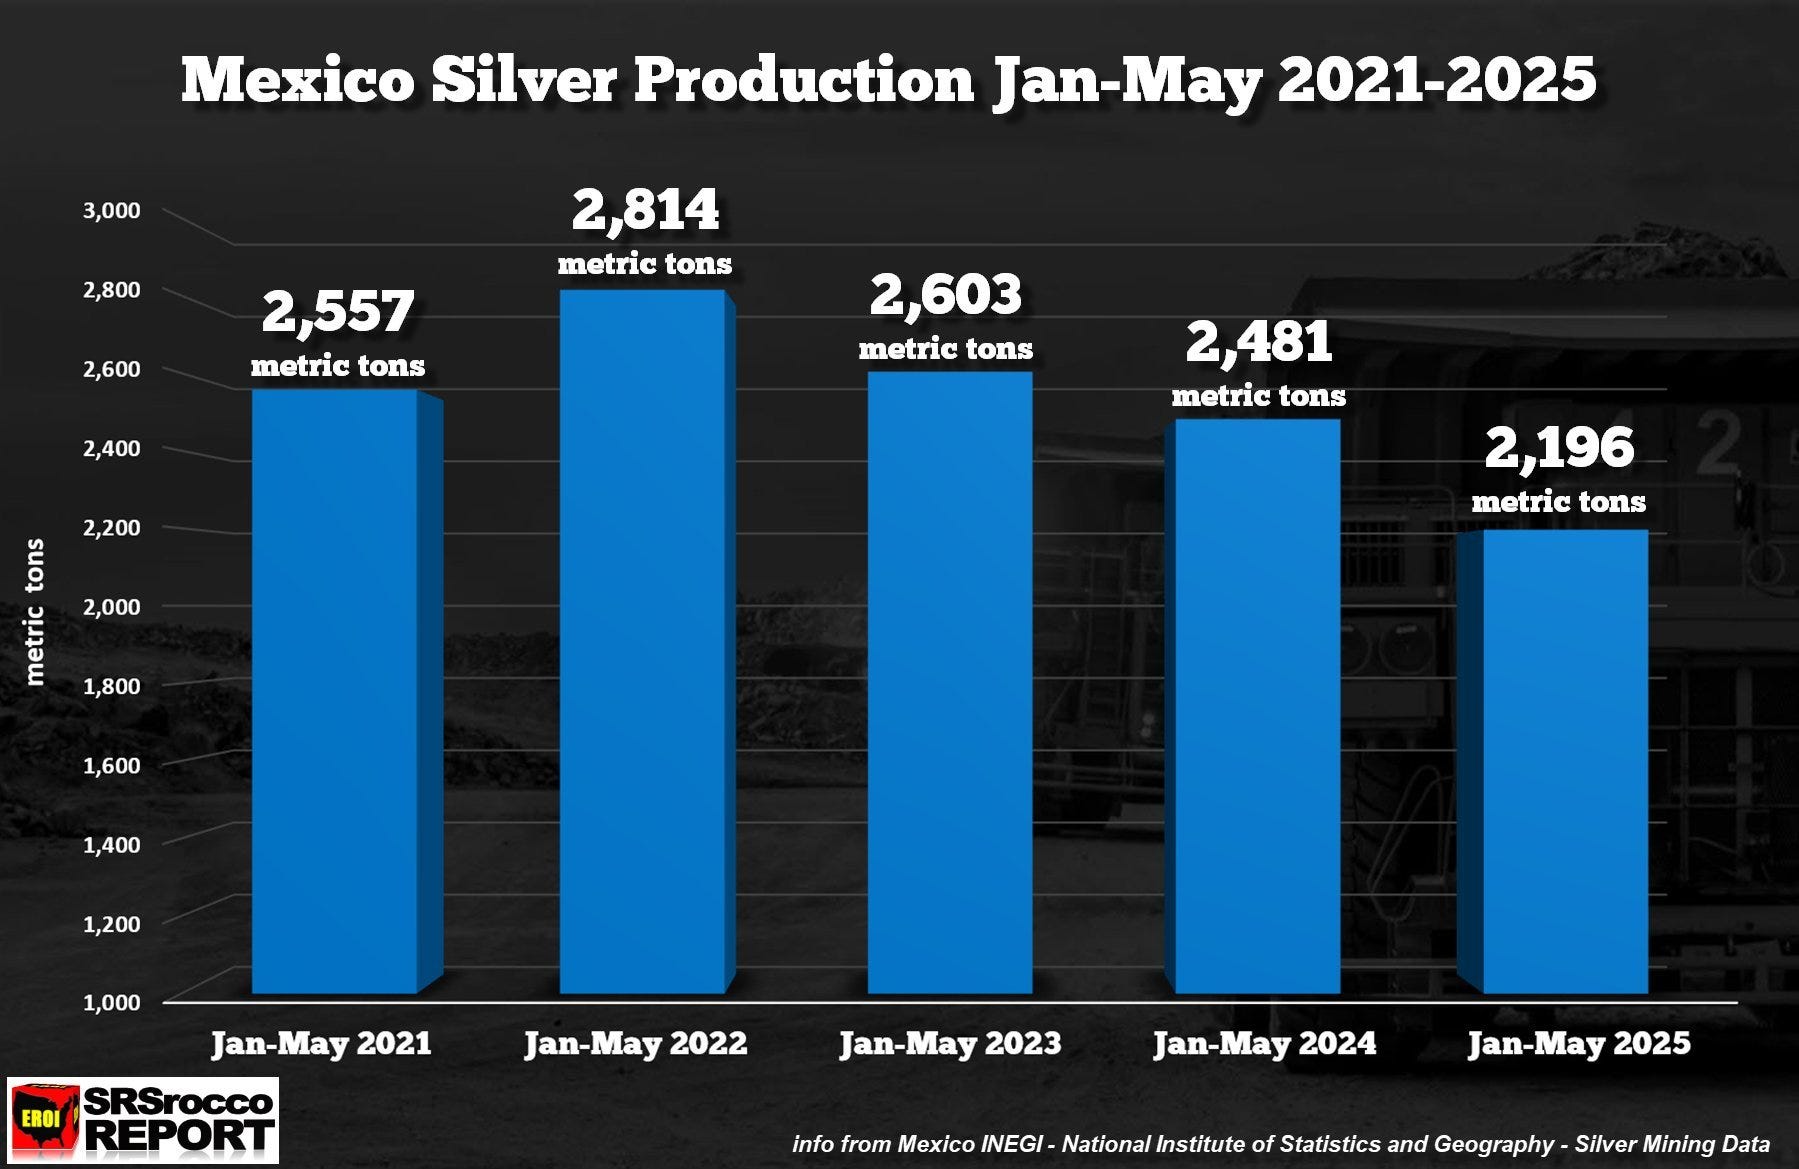
Let’s talk supply shock. Mexico, the world’s #1 silver producer, is in a “fall-off-a-cliff” moment. The Morena Party’s aggressive policies have driven up fees, taxes, and regulatory inspections, strangling foreign miners and halting new concession approvals. The result? Leading miners are hemorrhaging output:
-
First Majestic: Q1 2024 production dropped 32% year-over-year and 22% quarter-over-quarter. Their Mexican operations alone reported a staggering 24% quarter-over-quarter collapse in silver output as ore grades and throughput declined.
-
Endeavour Silver: Q4 2024 saw silver production plummet 41% year-over-year due to processing failures and operational mishaps, ultimately delivering 7.6 million silver-equivalent ounces, at the very bottom of revised guidance.
-
Newmont: Output continues to slide, handicapped by labor disputes and strategic shutdowns, with a dramatic production drop of 39% YoY in 2023.
Even Fresnillo, once a stalwart, has seen numbers sink. And it’s not just Mexico. Regulatory crackdowns, environmental pressures, and tax hikes worldwide are tightening the noose on new supply.
Jurisdictional Shifts and the New Winning Regions
With Mexico stumbling, investors are pivoting to safer, high-quality mining jurisdictions. The world’s top five for silver now: Bolivia, Morocco, Peru, the United States, and Canada. These nations boast high-grade ore bodies, superior governance, and friendlier regulatory frameworks for long-term capital.
Ray Dalio: The Silver Setup is “Explosive”
Legendary macro investor Ray Dalio has sounded the alarm: the risks are not yet priced in. This is a textbook “explosive setup”—a rare alignment of declining supply, record demand, and macro stress. Dalio points to the collision of long-term fundamentals and short-term triggers: “This alignment is rare, and when it happens, it changes how the entire market behaves. … The story of silver right now is not just about price—it’s about a structural mismatch between how much of it the world needs and how little of it the world can produce. That recognition, when it becomes widespread, is what transforms a slow, quiet imbalance into a decisive turning point”.
Catalyst: When Recognition Hits, the Move is Violent
The real opportunity isn’t just about “owning metal”—it’s about catching the turning point when the world wakes up to what’s happened. As Jon Little explains, “Markets can ignore reality for a long time. But when the collective awareness shifts, it happens fast. Liquidity floods in, volatility spikes, and positions that were manageable become untenable … The disciplined player is the one who understands the underlying structure.”
Silver Miners: Maximum Leverage Ahead
When you buy silver miners today, you’re not just buying ounces in the ground. You’re buying maximum leverage to this supply-demand reset. The majors are trading at multi-year valuation lows—vastly under-owned, underappreciated, and with potential upside measured in multiples, not percentages. Dalio and Costa both highlight institutional flows just now ramping up as retail remains on the sidelines. “Game on.”
The setups that legends like Dalio and Costa describe do not come around often. Silver’s supply is tightening year over year, above-ground stockpiles are thinning, and demand is relentless. This is a market where even a modest flow of new capital can ignite a historic rally. With macro, monetary, and industrial forces converging, now is the time to position—before “scarcity” becomes the new global narrative.
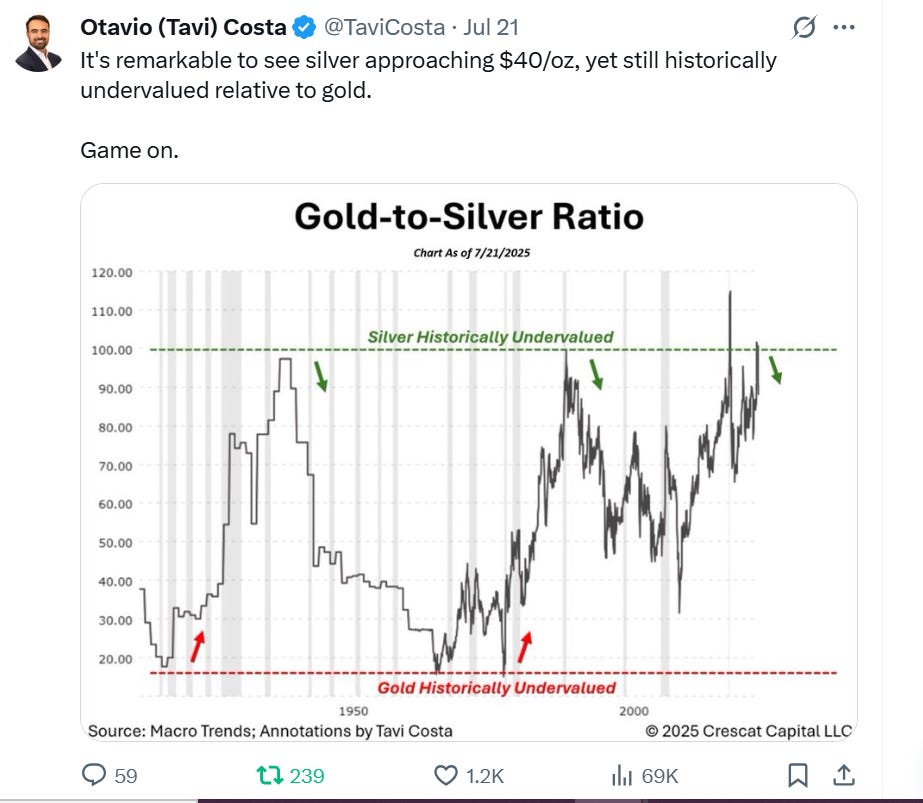
A narrowing gold-to-silver ratio is the fuse for an explosive silver rally. With gold forecasted to reach $4,000 by early 2026, even a mean reversion of the traditional ratio—historically near 50:1—would catapult silver sky-high. At $4,000 gold, a 50:1 ratio implies $80 silver, more than double today’s price. Legendary investor Eric Sprott highlights that past ratios around 100:1 are unsustainable, seeing a historic opportunity for outsized silver gains as the relationship normalizes.
Sprott argues, “A return to even 50:1 will ignite a run.” As powerful forces converge, investors see silver’s potential for dramatic outperformance as market psychology resets and institutional capital floods in
Silver Academy endorses three standout miners—Andean Precious Metals, Aya Gold & Silver, and Kuya Silver—because they perfectly embody the qualities legendary investor Eric Sprott seeks: exceptional ore grades, large in-ground silver resources, strong jurisdictions, robust metallurgy, high-purity silver focus, and minimal byproduct dilution.
-
Andean Precious Metals operates in Bolivia at the San Bartolomé mine—one of the largest oxide silver plants in the country—offering long mine life and high recoveries. Its commitment to local partnerships and efficient metallurgy amplifies its appeal. Ticker: TSE: APM, OTC: ANPMF
-
Aya Gold & Silver is a pure-play Moroccan silver producer, running the high-grade Zgounder mine and several advanced regional projects. It is the only TSX-listed silver miner operating at scale in Morocco and continues to rapidly expand its resource base. Tickers: TSE: AYA, OTCQX: AYASF.
-
Kuya Silver develops two high-grade silver districts: the Bethania mine in Peru—recently brought into production and currently ramping up—and the Silver Kings project in Ontario, Canada, within prolific historical silver camps. Both projects are advancing toward strong, primary silver production, not as byproducts. Tickers: TSE: KUYA, OTC: KUYAF.
These three miners score high on every front Eric Sprott highlights: they are silver-first operations, in mining-friendly regions, with excellent grades and scalable reserves—offering investors maximum leverage to surging silver demand and tight global supply.
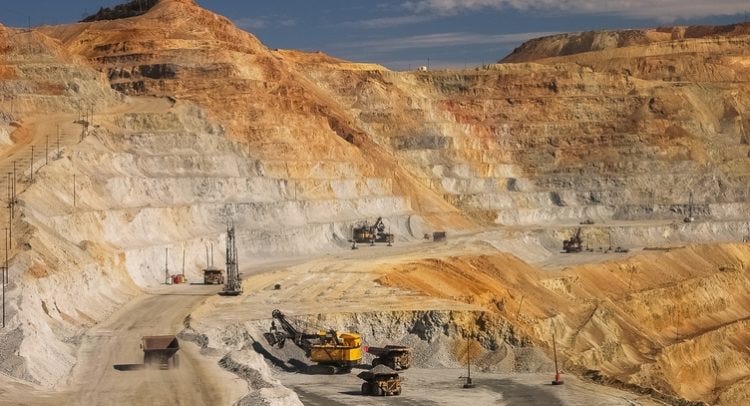
Andean precious metals. High grade silver in prolific Potosi silver mining district
end of segment
-
our opinions are not our sponsors
-
editorial department is separate from promotions department
-
not financial advice
-
Buy Silver (physical and silver miners listed above)
-
Don’t believe me but you should listen to Ray Dalio (video below)