
Stephen St. Angelo writes,
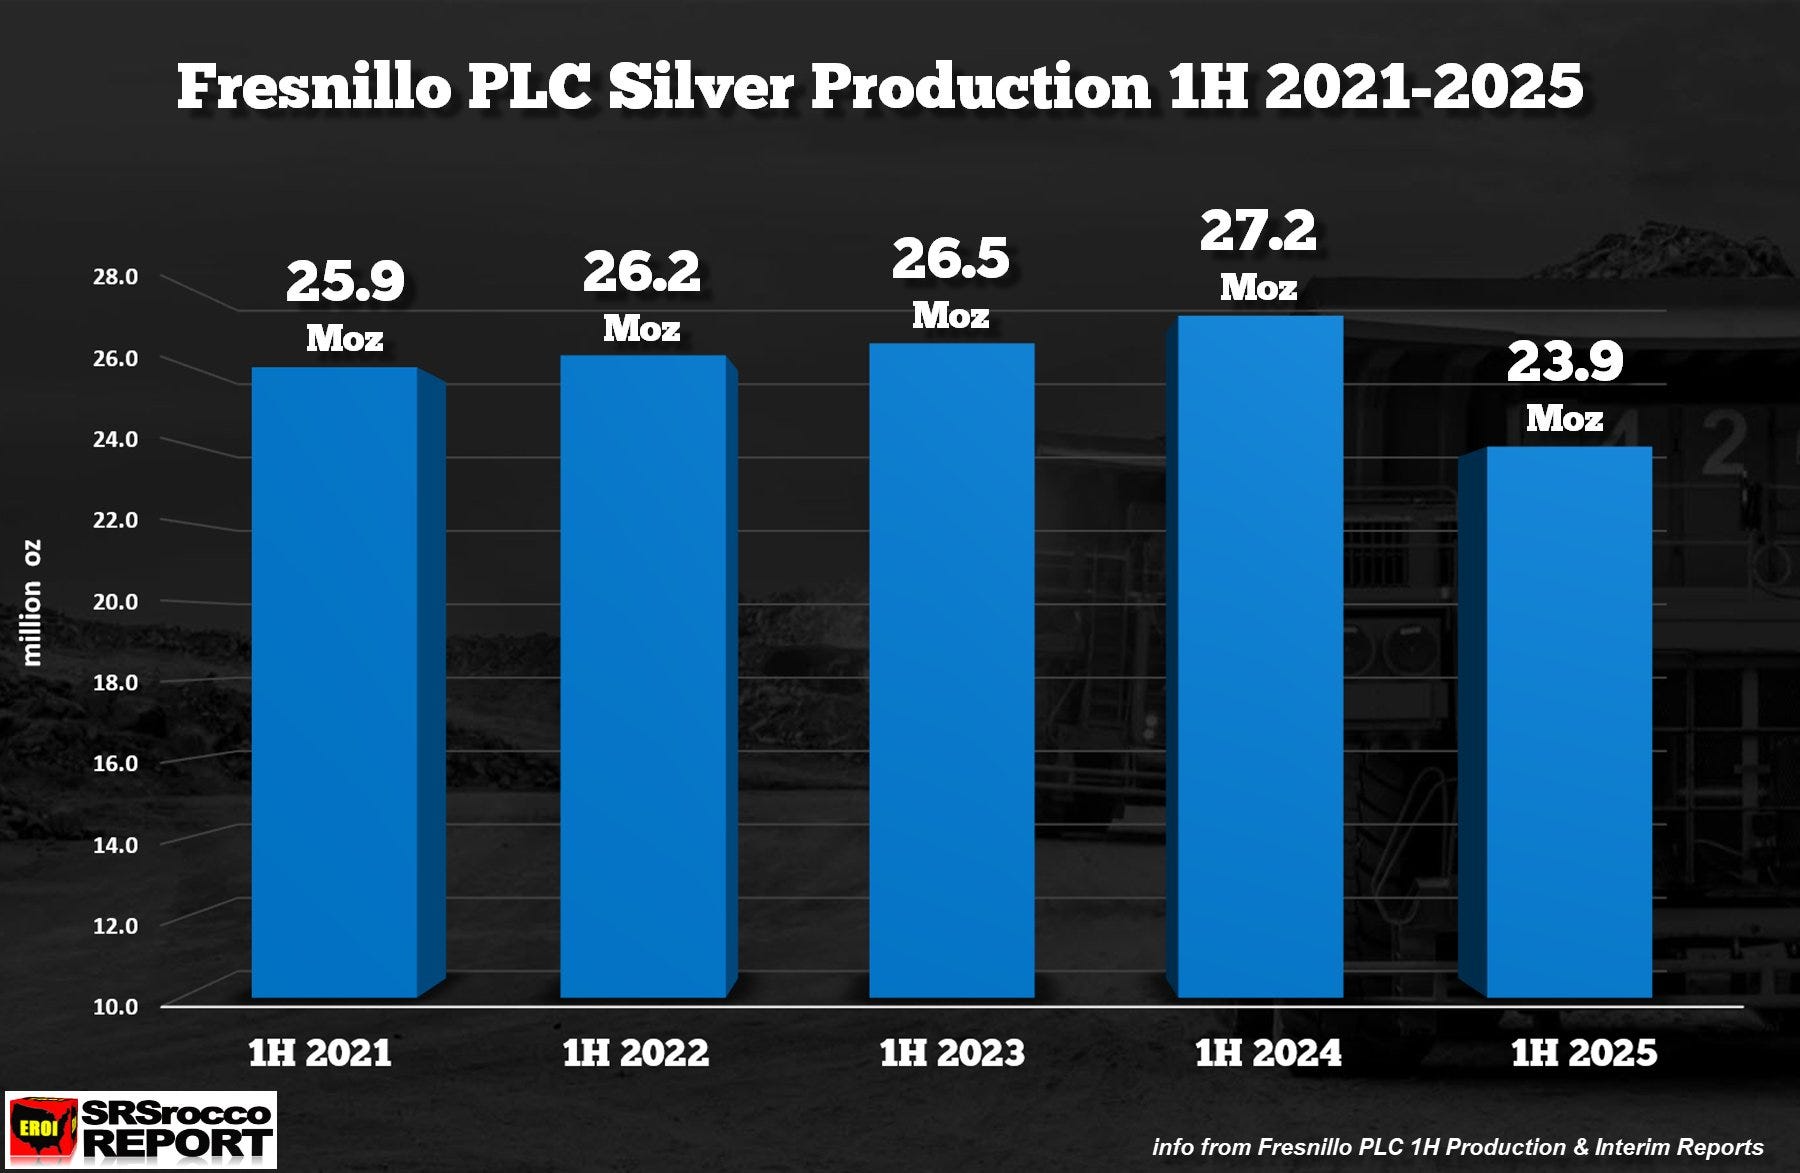
”The Decline In The World’s Largest Silver Miner Begins… Fresnillo PLC Reported 12% decline in 1H 2025 Silver Production. Global Silver Mine Supply to continue declining in the years ahead.”
Mexico’s Silver Slump Sends Shockwaves
The world’s largest silver miner, Fresnillo PLC, recently reported a sharp 12% decline in its silver production for the first half of 2025. While at first glance this might seem like a temporary setback, the significance reverberates far beyond Fresnillo’s balance sheet or even Mexico’s borders. Mexico produces roughly a quarter of the global silver supply—when production here declines, it triggers consequences for the entire world.
Silver Under Lock and Key
Fresnillo’s drop in output is not a one-off event, but part of a broader pattern. The company’s outlook for the rest of 2025 anticipates continued decline, partly due to lower ore grades and the closure of some mining operations. Even more troubling, these setbacks are occurring against a backdrop of sweeping policy changes: President Claudia Sheinbaum’s government, building on her predecessor’s nationalist agenda, has completely halted the issuance of new mining concessions in Mexico. The aim is clear: defend strategic resources and bring more of the country’s mineral wealth, especially silver, under state control. After recent nationalizations in lithium and electricity, the question is no longer if silver will be nationalized, but when.
Investor Chill: Global Ripples
This evolving political environment in Mexico sends an unmistakable warning signal to the silver industry and investors worldwide. Nationalization is now widely seen as inevitable, and with it comes restrictive licensing, higher regulatory hurdles, and escalating uncertainty for foreign companies. As foreign investment retreats and mine expansions stall, the world’s access to new silver dwindles just as demand is reaching record highs.
Why You Can’t Just Dig More Silver
Bringing new silver inventories online is far more complicated than simply “digging more.” Developing a major mine is a drawn-out, expensive process often taking up to a decade or more, requiring discovery, lengthy permitting processes, local consent, massive capital outlays, and a stable political environment. With Mexico’s doors effectively closed and other major producers like Chile and China also tightening regulations or facing social resistance, there are very few large-scale projects ready to fill the gap left by Mexico’s waning production.
This is precisely why we endorse Aya Gold and Silver, (Morocco) Andean Precious Metals, (Bolivia) and Kuya Silver (Peru) .
– all three in production
– all three have over a decade of mineral resources remaining underground
– all three in superb jurisdiction
– all three utilizing best practices surrounding geology and metallurgy
– all three screaming buys and poised to jump 10x to 20x over next 2 years since demand is intensifying and Mexico is stalling.
The Nationalist Tsunami: No Safe Havens
Globally, resource nationalism is on the rise, especially in Latin America and parts of Asia and Africa. Governments are demanding bigger shares of mining profits, increasing taxes and royalties, and sometimes even threatening to revoke existing contracts. Meanwhile, environmental standards are getting stricter and public resistance to new mines is growing, lengthening development timelines, and in some cases, blocking projects entirely.
Silver: Technology’s Secret Ingredient
All of this is happening just as silver demand is surging to unprecedented levels. The metal’s unique combination of properties—unmatched electrical and thermal conductivity, exceptional reflectivity, and excellent malleability and ductility—makes it indispensable in an era increasingly defined by electronics, clean energy, and advanced manufacturing. More than 80% of silver demand now comes from industrial uses, a dramatic shift from only a few years ago. Every solar panel, electric car, 5G antenna, advanced battery, precision robot, and next-generation military system relies on silver to function efficiently. In fact, the solar industry alone is projected to consume over 80 million ounces of silver per year, and that figure climbs as installations accelerate globally. The rise of solid-state batteries, including those developed by companies like Samsung, further underscores silver’s growing strategic role.
Tidal Wave of Demand, Drought of Supply
In 2024, global industrial silver usage hit an all-time high of over 680 million ounces. Forecasts for 2025 anticipate this total will surpass 700 million ounces, with green energy and electronics poised to consume nearly 900 million ounces over the next decade. Yet, mine supply continues to shrink, down more than 7% since 2016, and above-ground stockpiles are steadily eroding as persistent supply deficits—between 117 and 149 million ounces annually—force the industry to dip into reserves. Recycling has increased, but it cannot keep pace with the loss of fresh mined silver.
Mexico: The Silver Canary in the Coal Mine
The situation in Mexico isn’t just a national story—it’s a bellwether for the entire global silver market. Declining output from the world’s top producer, a freeze on new mining concessions, looming nationalization, growing operational risks, and rising industrial demand all point to a historic tightening of supply. Modern economies now depend on silver more than ever, and yet it is becoming increasingly difficult—and politically fraught—to find, mine, and deliver new supplies.
Countdown to a Global Silver Squeeze
The world is heading toward a profound and potentially prolonged silver shortage. What unfolds in Mexico will ripple through industrial supply chains, global markets, and even international geopolitics. As demand charges ahead and supply struggles to keep up, the question is no longer “Will silver become scarce?” but “How will the world adapt to silver scarcity?”
Silver Academy Endorsed Miners & Tickers
The Silver Academy highlights three primary silver miners in production and two junior miners advancing key projects. Each company’s OTC and TSX tickers are provided for reference.
Primary Silver Miners
-
Aya Gold and Silver (Morocco)
-
OTC: AYASF
-
TSX: AYA
-
We see Aya Gold and Silver blowing way past its 52 week high of $14.18 by Thanksgiving 2025. That is a conservative 38% to the upside climb
-
Andean Precious Metals (Bolivia)
-
OTC: ANPMF
-
TSX: APM
-
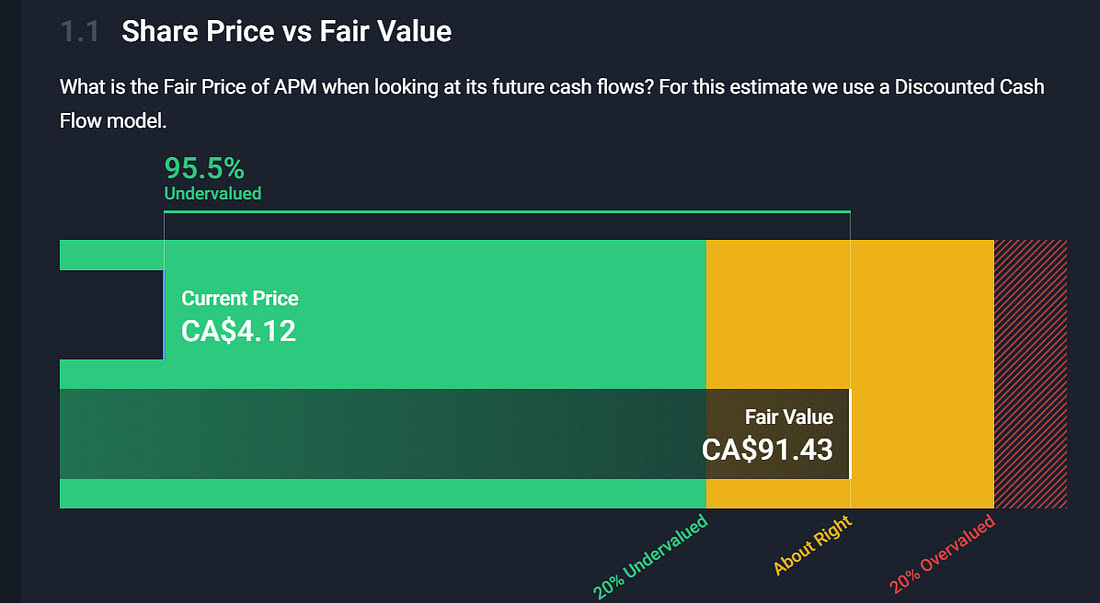
We have Andean Precious metals still over 95% undervalued
-
Kuya Silver (Peru)
-
OTC: KUYAF
-
TSX: KUYA
-
Q2 operational highlights, including an 87% increase in mineralized material processed and a 63% increase in underground development, marking steady progress toward our Phase 1 target of 100 tonnes per day.
end of segment