
Silver is #1 conductor and transmitter of ALL FUTURE ENERGY
China’s ongoing clean energy revolution has reached remarkable new milestones in 2025, marked by an extraordinary surge in solar power installations. The country’s total installed solar photovoltaic (PV) capacity is projected to climb to nearly 900 gigawatts (GW) by the end of 2025, an increase of almost 37% from the previous year. With government targets setting the bar high, installed solar capacity is expected to exceed 1,000 GW—one terawatt—by 2026. The long-term national goal stretches even further, aiming for 1.7 terawatts by 2030.
Solar energy has grown to contribute more than 30% of China’s total power generation capacity and is now supplying over 12% of national electricity output during peak solar months. Notably, in April 2025, wind and solar together provided 26% of the country’s monthly electricity. This development marks the first time that renewables have overtaken fossil fuels in China’s installed capacity. Major provinces such as Shandong, Henan, Hebei, and Jiangsu lead in solar deployment, with each boasting solar installations surpassing 50 GW—putting them ahead of most countries globally. The expansion covers both vast desert-based utility projects and an increasing number of distributed rooftop systems across commercial and industrial sectors.
China’s influence is not confined to its borders. The country is responsible for adding over 40% of the world’s new solar capacity each year, and projections indicate that in 2025 it will install more solar power than the rest of the world combined. This momentum is fueled by robust investment—solar PV investments reached $15.8 billion in the first half of 2023, significantly outpacing spending on thermal power. Major efforts are underway to upgrade power grids and expand energy storage, particularly pumped hydro, which is expected to reach 64 GW by the end of 2025.
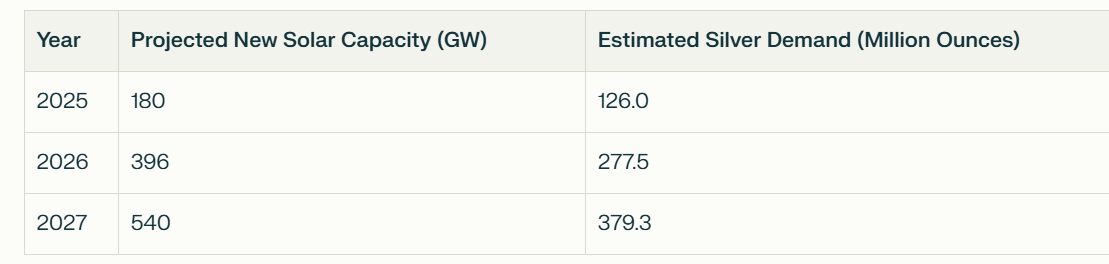
Projected Annual New Installations and Corresponding Silver Demand
The rapid advancement of solar energy is having a profound effect on material supply chains. Silver, with its unmatched electrical conductivity, is essential for photovoltaic cell manufacturing, and its demand is surging in tandem with China’s solar expansion. Industry experts estimate that approximately 700,000 ounces of silver are required for every new gigawatt of solar capacity installed.
The table below summarizes the projected new solar capacity installations and the corresponding estimated silver demand for the years 2025, 2026, and 2027:
Over the course of these three years, the cumulative demand for silver from China’s solar sector could reach approximately 783 million ounces. This phenomenal growth in solar installations not only highlights the country’s commitment to renewable energy but also points to rising pressure on global silver supplies as the solar build-out accelerates.
China’s strategy, powered by forward-thinking policy, robust provincial leadership, and continual technological innovation, is fundamentally reshaping not only its own energy landscape but also exerting considerable influence on global markets. As demand for renewables rises, so too does the need for critical raw materials such as silver, signaling potential strain on supply chains and a new era of competition for essential resources.
The world is on a solar binge—at precisely the moment its most critical ingredient is running on empty. By 2030, solar panels alone are projected to consume a jaw-dropping 65% of global annual silver supply, up dramatically from just 15-16% in 2023. This isn’t a minor detail on the outskirts of the green revolution. It is a structural shift—a tectonic remapping of industrial resource flows that underpins the future viability of clean energy.
Based on the media blackout on this subject, you might ask, should we care?
Because the photovoltaic (PV) cells that form the nervous system of solar panels simply cannot function without silver. Unlike copper or aluminum, silver offers unmatched electrical conductivity, unrivaled reflectivity, and malleability—a triumvirate of properties that make it wholly irreplaceable in high-efficiency solar technology. If you think this is a niche problem, consider this: there is no true rival to silver in next-generation PV efficiency. So, can we afford to stake our planetary decarbonization agenda on an element with no substitute?
Now, layer on the next factor: global solar capacity is poised to triple, perhaps even quadruple, by 2030. Nations are locked in a breakneck race for energy independence and decarbonization. The resulting surge in demand means solar alone could soon gobble up 160–200 million ounces of silver—every single year. Let that figure settle in: this is not merely more solar panels. It is a massive, nearly exponential rise in the appetite for a finite, non-renewable resource.
So, what happens to supply amid this insatiable demand?
Here’s the hard truth: supply is structurally flat. Total annual silver mine production has hovered around 820–830 million ounces in recent years, affected by mine suspensions, labor strikes, and declining ore grades. Even if every operating mine in Mexico, China, Peru, and beyond churned at peak efficiency, there is no breakthrough in sight—no silver spigot waiting to be opened to flood the world’s supply.
Will recycling save us?
No. Recycling accounts for a paltry 15–20% of total annual supply, and this number has barely budged despite a decade of soaring demand. The brutal fact is that silver’s embedded use in solar cells, electronics, and medical devices makes it uneconomical—sometimes technologically impossible—to recover at scale. Most of what enters industrial devices is gone forever, sequestered in scrap, landfills, or in quantities too small to extract profitably. Can we bank our energy future on hypothetical advances in recycling that, so far, are losing the economic race?
Zoom out, and the clouds gather. Solar is no lone actor. Industrial demand for silver—from electric vehicles, electronics, *military systems, aerospace, 5G networks, AI chips, robotics, electric trains, and next-gen batteries—competes head-to-head with solar.
*
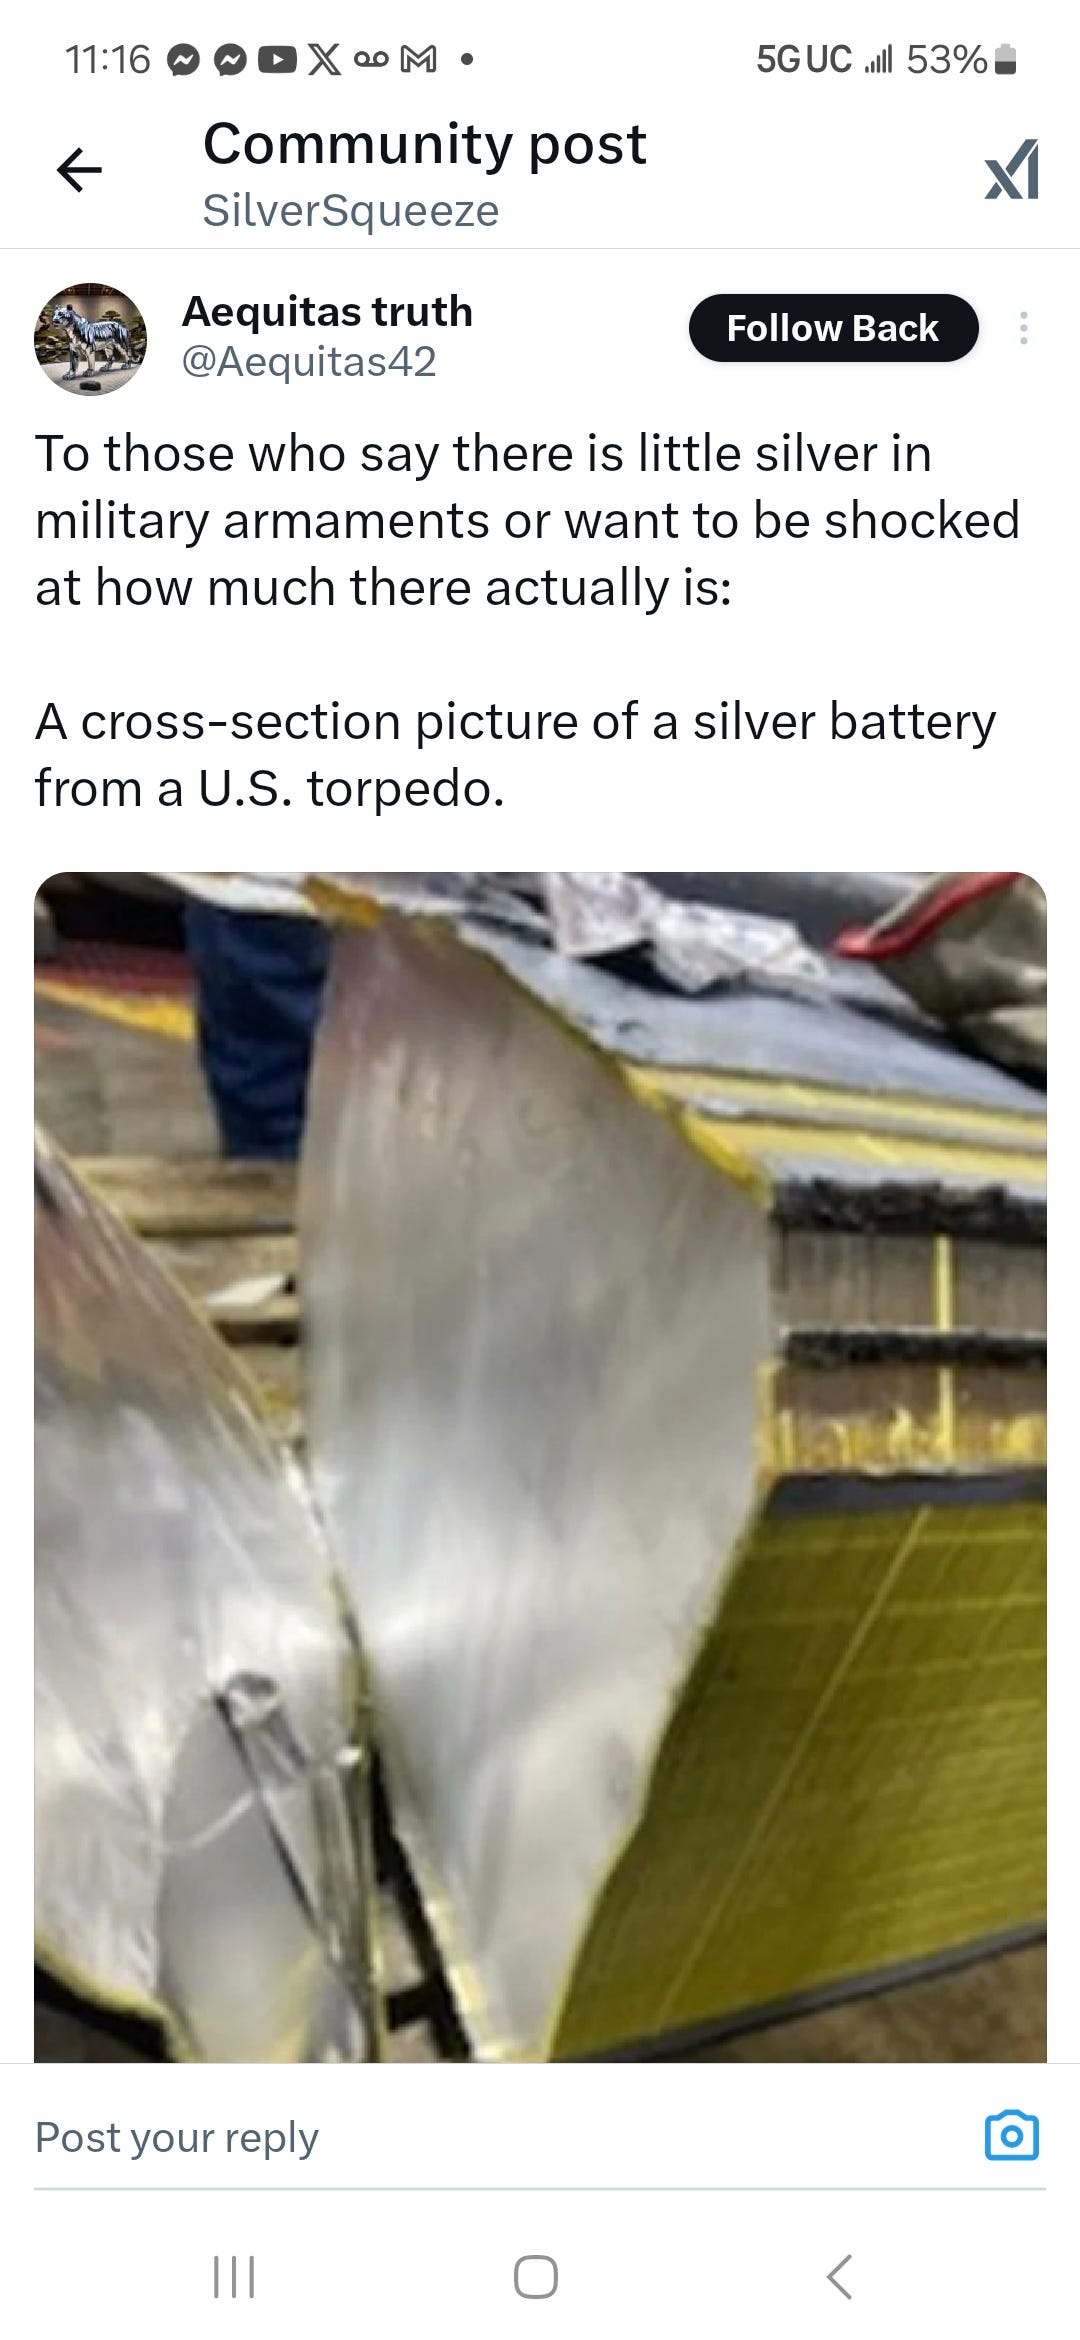
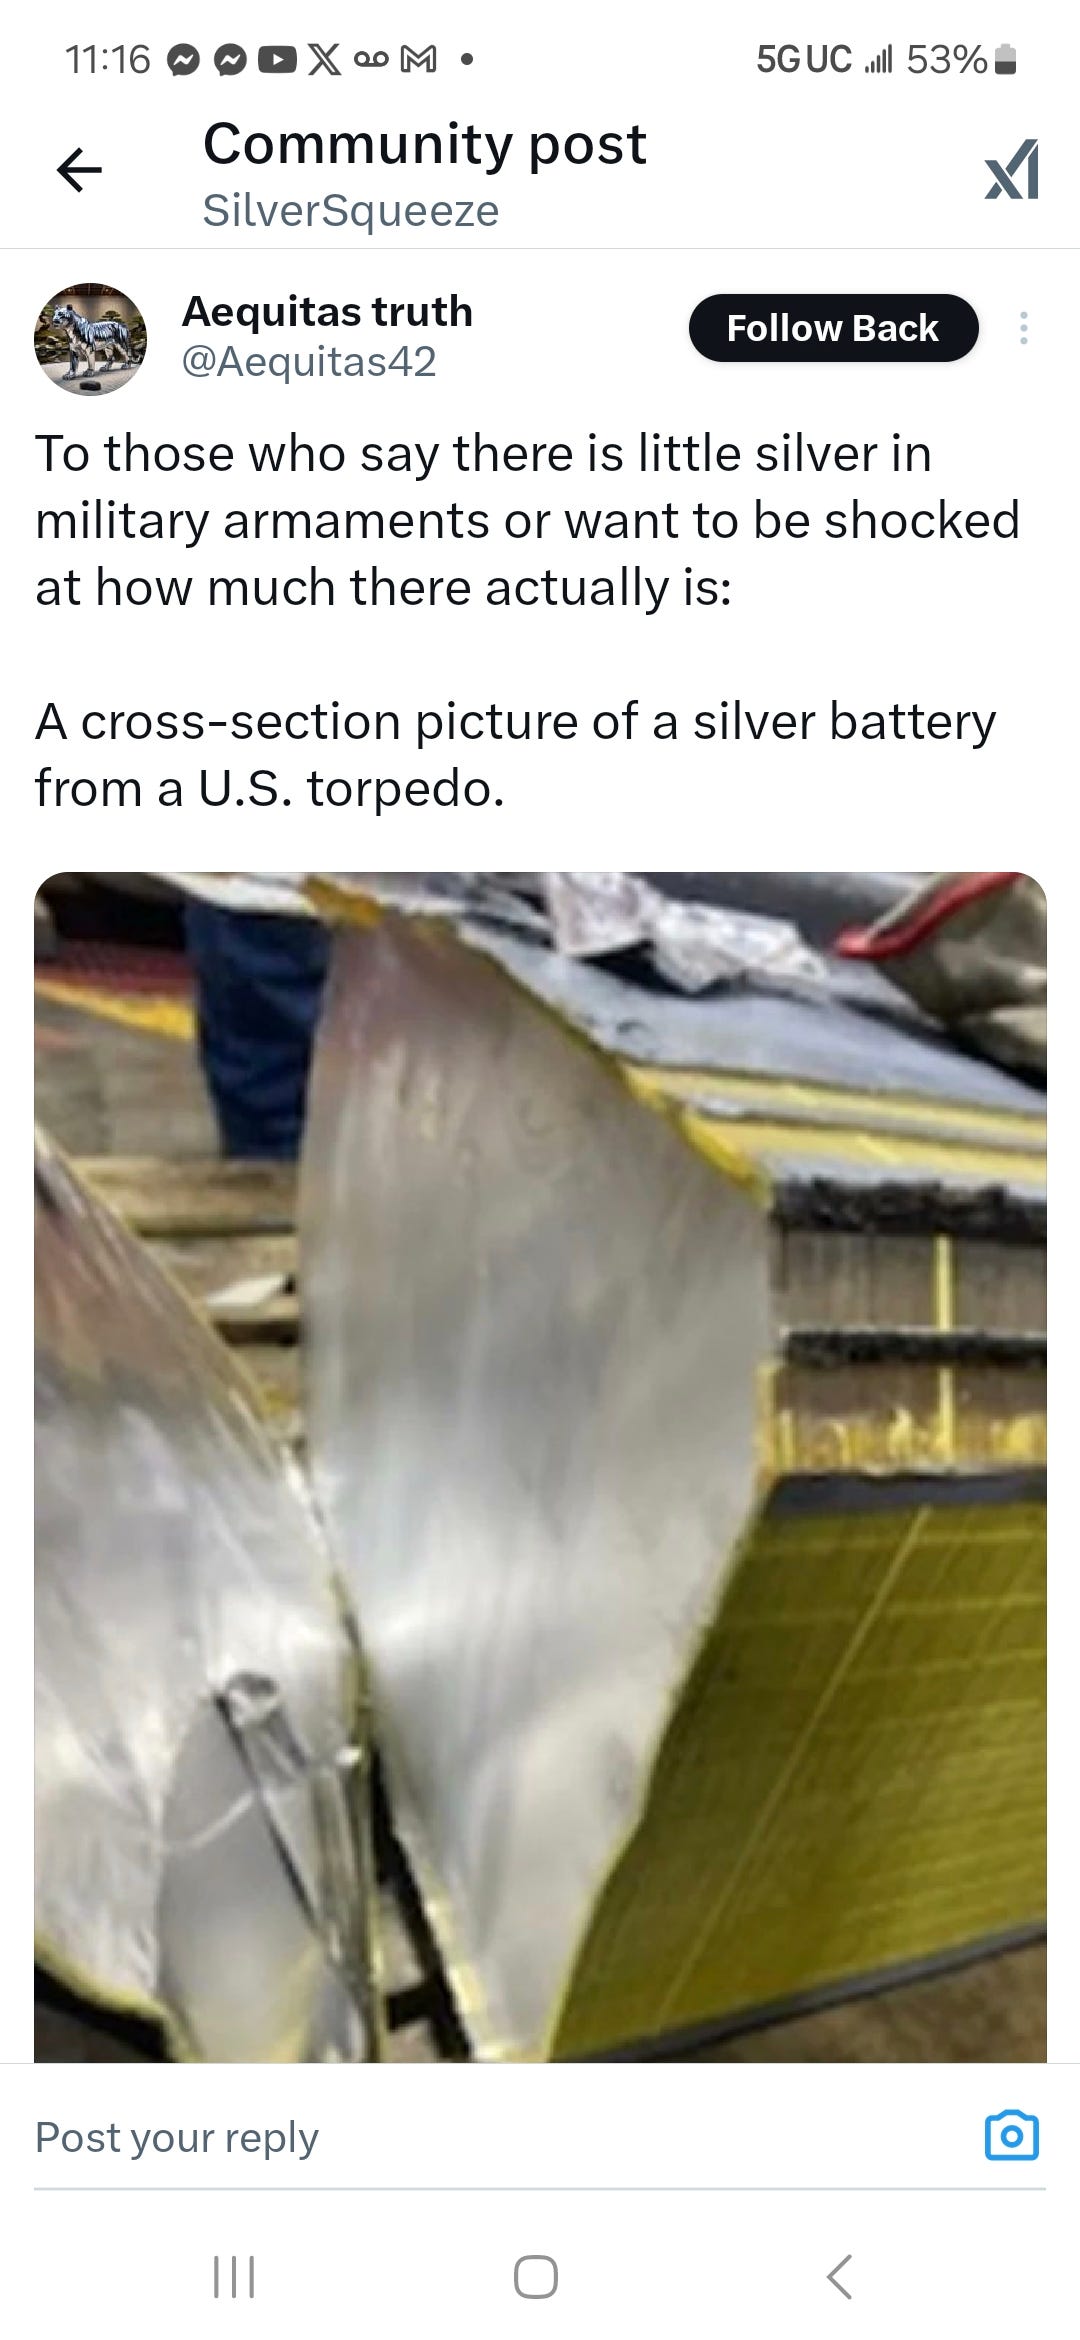
In military applications, some silver-zinc batteries contain 11,000 ounces of silver and are as large as two typical basement water heaters. These batteries are essential for powering massive missiles, bombs, and torpedoes because only silver enables reliable performance in extreme conditions. Lithium-ion batteries fail in severe weather—which is why news frequently shows Teslas catching fire or exploding during Florida hurricanes. Humidity and lithium are incompatible. In contrast, silver batteries can operate fully submerged in water, such as in torpedoes, and withstand both the intense heat of space and the severe cold unattainable on Earth. – Jon Forrest Little
Don’t believe us, watch the video below. These Silver and Zinc batteries are so massive they require mechanical lifts, chains, pulleys, forklifts. 11,000 ounces of silver is a conservative figure, some specs double that number.
At the same time, investors, wary of monetary debasement and persistent inflation, are scooping up coins, bars, and ETFs as a hedge against currency debasement. This double squeeze—soaring industrial consumption and resurgent investment demand—leaves the physical silver market exposed to persistent shortages. Are you prepared for what comes when industry and investors battle for the same ounce of silver?
Some pundits wave off concern with breezy optimism: “We’ll just find more silver. We’ll ramp up recycling.” Reality check: bringing a new silver mine online takes 7–10 years—even if everything goes right. Meanwhile, mining is becoming costlier, riskier, and more geopolitically fraught. As for recycling, today’s processes remain prohibitively expensive for extracting trace silver from thousands of tons of e-waste or solar scrap, with costs far exceeding spot prices.
Ask yourself: when time is short and supply is fundamentally inelastic—can we afford to wait?
Oil, for all its faults, is “spicket-based”: turn a valve, ramp extraction. Silver is not so kind. No flick of a switch will suddenly triple mine output or unlock latent stockpiles. The silver supply crisis is not looming—it’s here, and escalating each year a structural deficit persists. Will policymakers, investors, and the public wake up before the shortage bites?
Consider the consequences if we fail. Solar deployment bottlenecked by silver scarcity. Clean energy targets slipping out of reach. Industrial inflation where prices rise not just for trinkets but for the foundations of our electrified, digital future. And in the shadow of scarcity, the hoarders, speculators, and strategic stockpilers will move. What happens when the price of decarbonization is dictated not by policy or aspiration—but by the resource you can’t substitute, find, or make anew?
The future of energy independence and green transition pivots—quietly, inexorably—on the fate of silver. The alarm bells are ringing. Will we act, or hit the snooze button until it’s too late?
AI: The Energy Juggernaut That Dwarfs the Dot-Com Bubble
The AI boom is not just another bubble. It’s a ravenous juggernaut, making the dot-com mania look like child’s play. Artificial intelligence is devouring energy at a velocity and scale never before witnessed in the digital era—so much so that by 2030, data centers, fueled by AI’s insatiable needs, could command up to 20% of U.S. electricity demand, rivaling national consumption levels of countries like Japan or Turkey. In the past, “disruption” was just a buzzword. Now, it’s the grid itself—AI data centers are literally distorting America’s power flow, straining infrastructure, and sparking billions in damages as harmonics ripple through residential neighborhoods.
With power demand surging by 20–40% annually and traditional grid expansion lagging years behind, hyperscalers—those titans behind the AI arms race—are scrambling for a solution, one immune to grid blackouts, brownouts, or regulatory chokeholds. Why accept a regulator’s hand on the switch when the cost of downtime spirals into the millions per minute? For these operators, energy sovereignty is not a preference; it’s an existential imperative.
Enter solar energy, not as an environmental afterthought, but as the lifeblood of AI data center expansion. The business calculus is brutal: solar’s cost curve is plunging, its availability scalable, and, paired with battery storage, it offers round-the-clock, off-grid power with no counterparty risk and no utility veto. Data centers are now being built off the beaten grid path—on endless sun-soaked land, scaled with solar farms, armoured with batteries, and in some cases, insulated from every external lever of control. Automation, regulation-resistant. Uptime, absolute.
Ask yourself: When did infrastructure ever move this fast, or with such disregard for old rules? The answer is—never. The stampede to energy self-sufficiency isn’t just about keeping the lights on; it’s about rewriting the power playbook for a digital civilization on the brink. AI data centers bet on solar because it is the only way to guarantee sovereignty in an energy-starved world, a world in which waiting for grid upgrades or utility nods is the ultimate business risk.
So while the dot-com bubble was froth and pages, the AI surge is steel, silicon, and gigawatts. Entire regions are being reshaped by the gravitational pull of megawatt-hungry AI clusters that cannot—and will not—wait for yesterday’s infrastructure to catch up. The very future of digital power is going off-grid, fueled by the relentless sun, at the edge of any regulator’s reach.
end of segment