
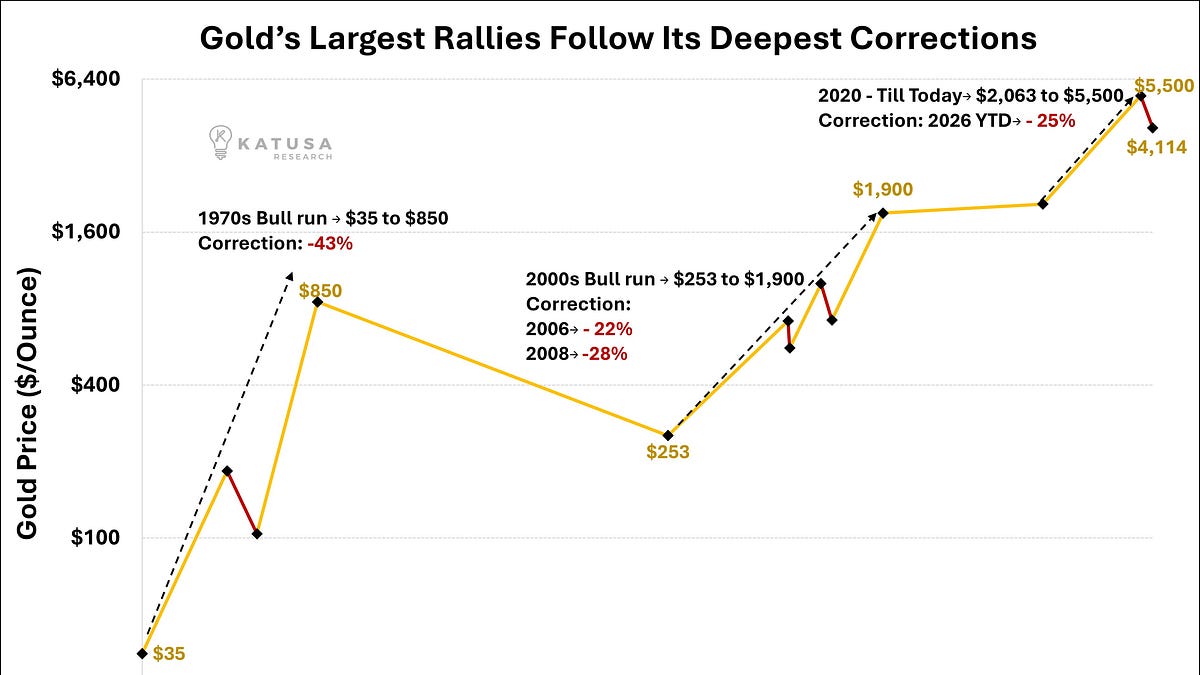
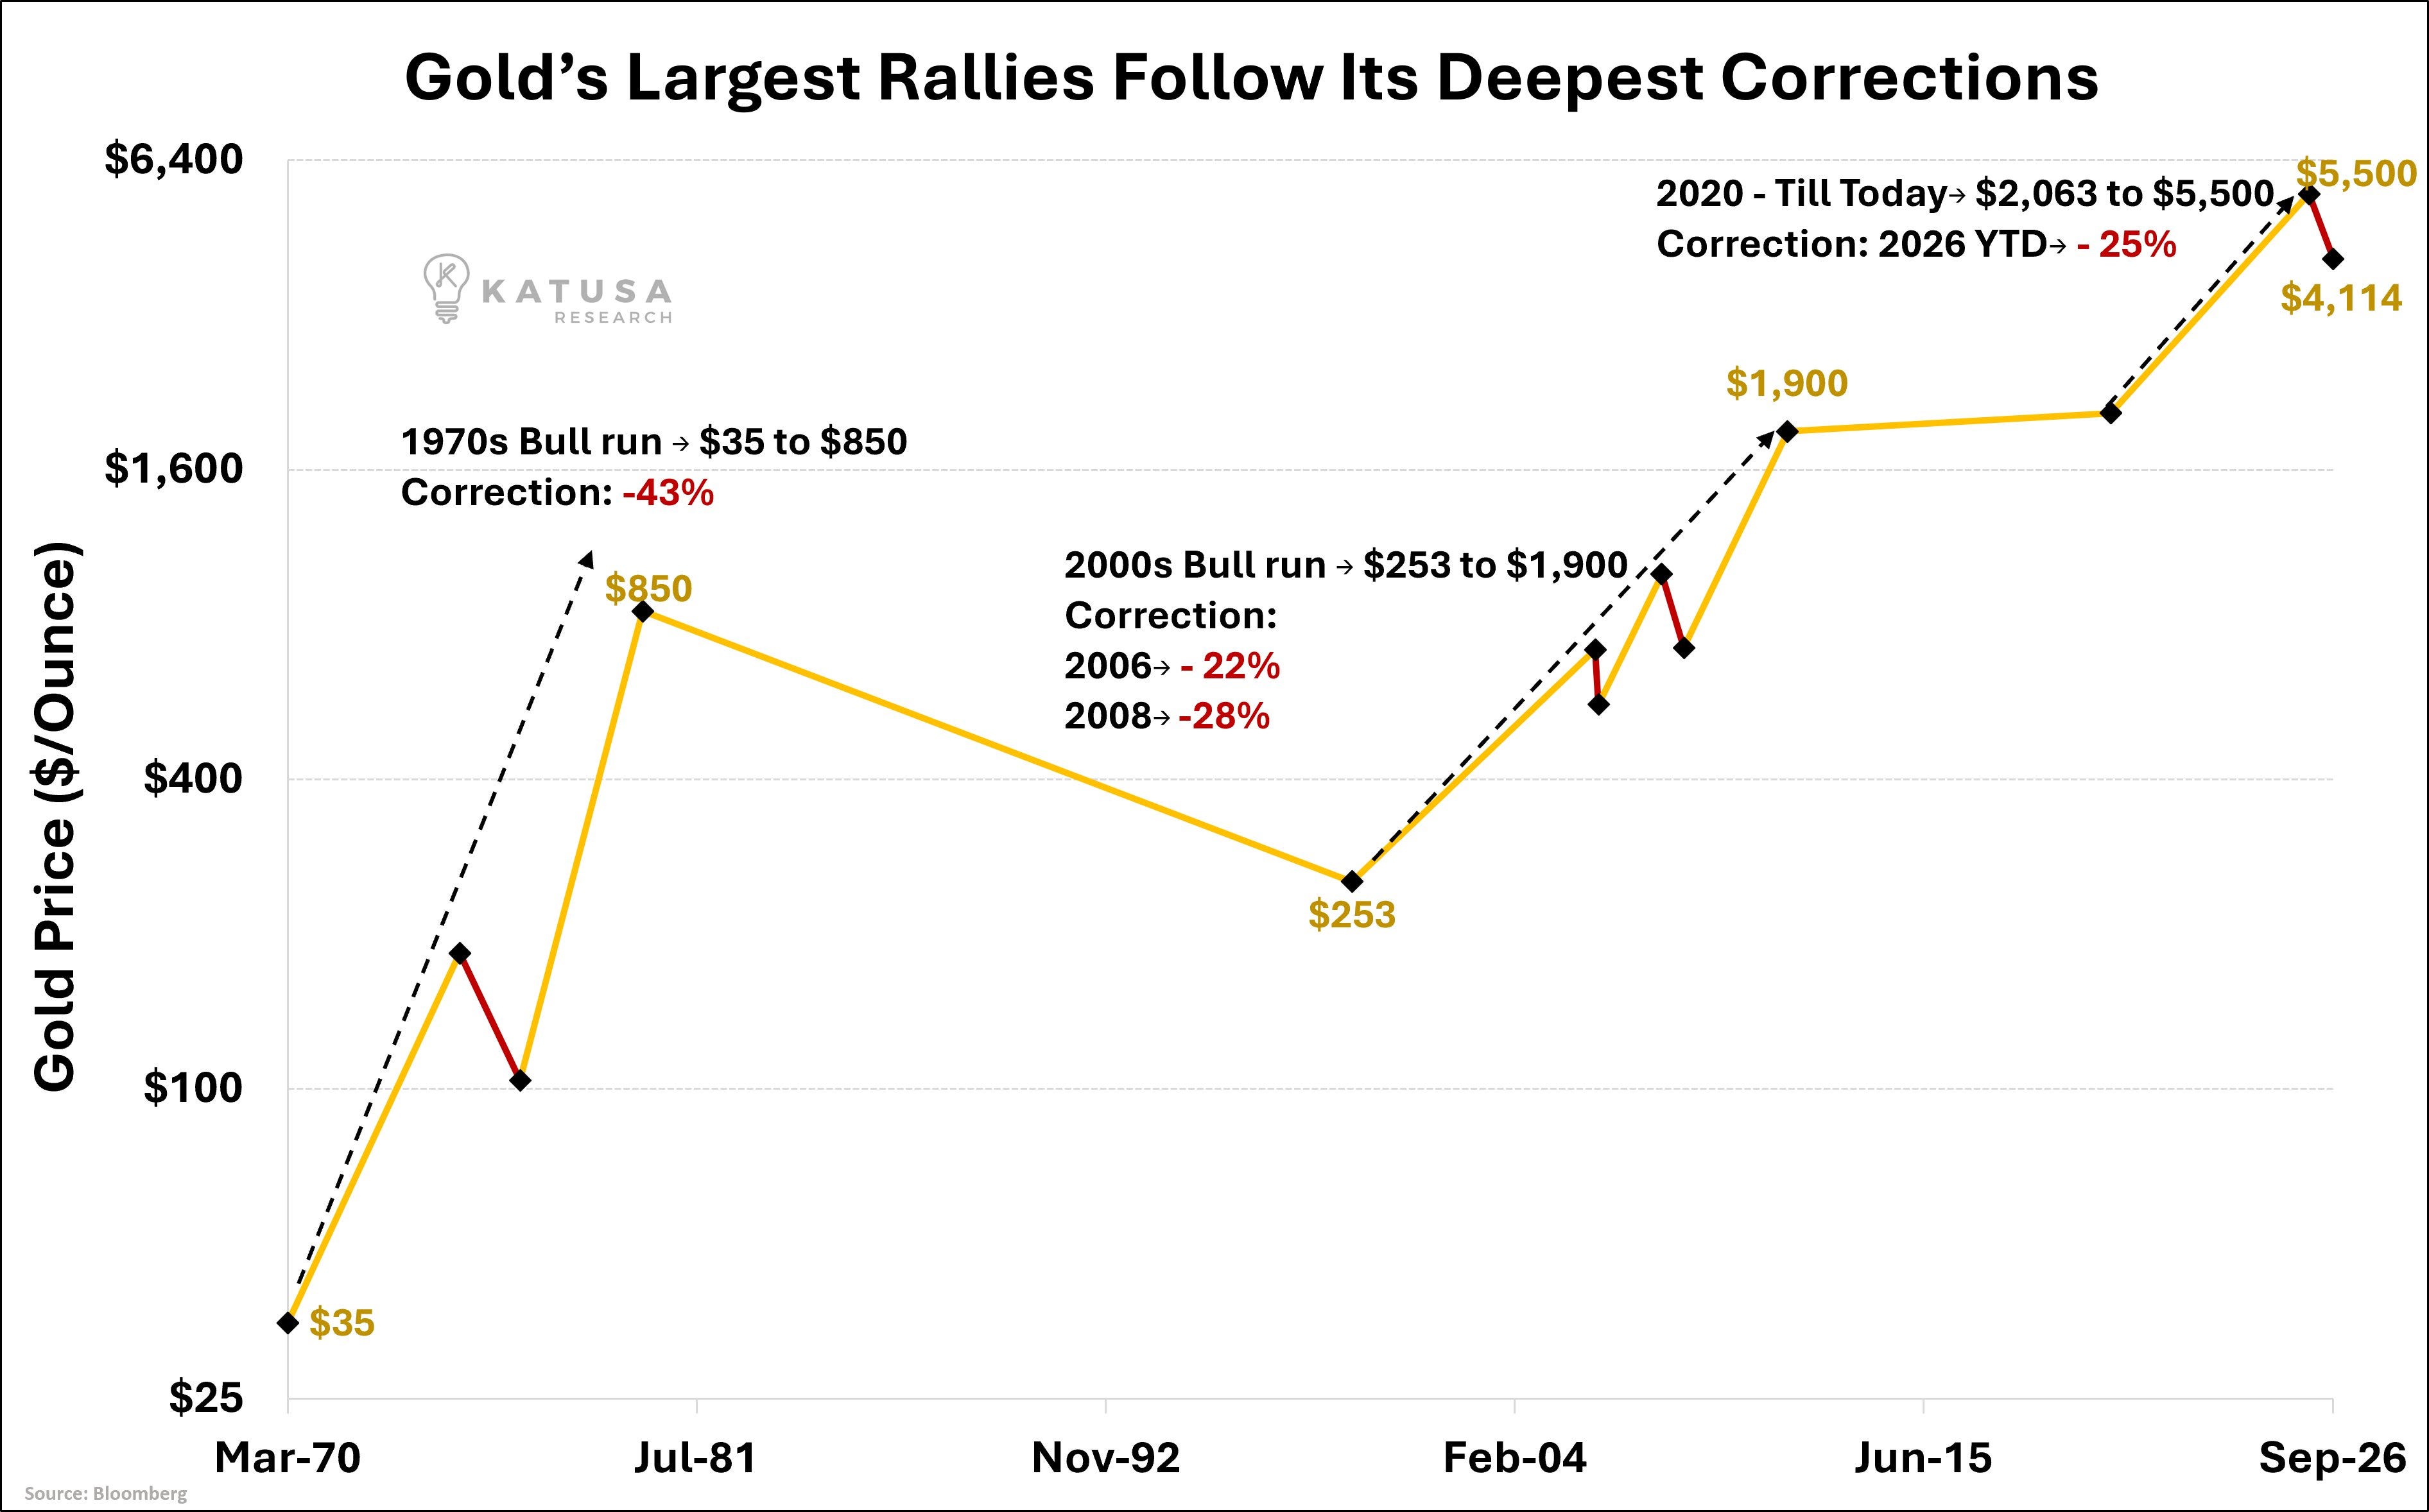
Recall the performance of commodities in the 1970s
-
Gold up 23X, 2,200%
-
Silver up 30X, 2,900%
-
Oil up 12X, 1,100%
Silver Miners Set to Soar: Buy the Dips After the Latest COMEX Shakeout
The latest paper-market slam should not distract investors from the bigger setup: physical silver remains constrained while demand from AI data centers, electrification, solar build-outs, EVs, and advanced battery technology keeps expanding. For investors who understand that volatility is the admission price for leverage, these four companies offer distinct ways to gain torque to a rising silver price.
Aya Gold & Silver (AYA)
Aya Gold & Silver (AYA) is a direct producer-leverage play anchored by Morocco’s rare silver-only Zgounder mine. Zgounder produced 1.49 million ounces of silver in the second quarter, up 43% year over year, while the company’s 2026 guidance calls for 5.2–5.8 million ounces. Beyond current production, Boumadine supplies the explosive upside: a large polymetallic project advancing through feasibility work with continuing high-grade drilling results.nasdaq+2
Andean Precious Metals (ANPMF)
Andean Precious Metals (ANPMF) is a Bolivia-based silver operator rooted in the legendary Potosí district, one of history’s great silver camps. Its San Bartolomé operation processes oxide material acquired through a deep local supply network connected to thousands of artisanal miners. That model offers unusual access to feedstock in a mineral-rich region. If silver keeps rising while global supply stays tight, each processed ounce carries potentially powerful operating leverage.
Kuya Silver (KUYAF)
Kuya Silver (KUYAF) is a high-grade, high-torque silver story centered on the Bethania mine in Peru. This is precisely the type of smaller producer that can move sharply when grades, recoveries, and output exceed market expectations. In a silver-deficit environment, Bethania’s high-grade ounces become increasingly valuable; higher realized prices can flow disproportionately into operating margins, cash flow, exploration budgets, and ultimately valuation.
Silver47 Exploration (AAGAF)
Silver47 Exploration (AAGAF) offers exploration leverage across three mining-friendly North American jurisdictions: Alaska, Nevada, and New Mexico. Its portfolio includes Alaska’s flagship Red Mountain deposit, Nevada’s Hughes project near Tonopah, and New Mexico’s Mogollon project. The company reports roughly 236 million silver-equivalent ounces in the inferred category plus 10.3 million indicated ounces across its projects, supported by a funded 2026 drilling program. This is not cash-flow leverage—it is discovery, resource-growth, and rerating leverage
China’s Gold Trap Is Closing
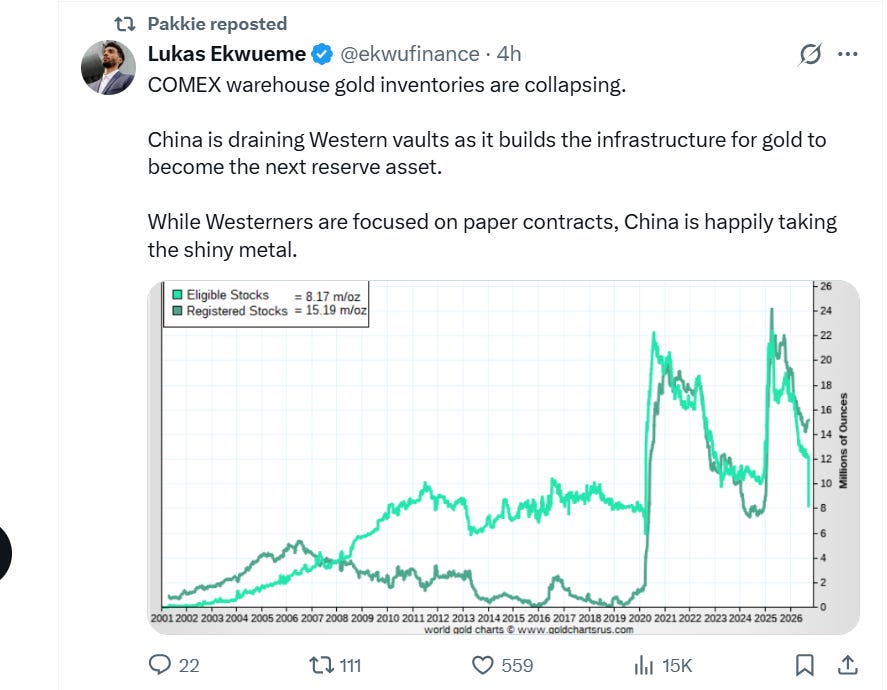
China is not simply buying gold. It is assembling a physical-metal strategy that challenges the paper promises beneath the dollar-based financial order.
The formula is deceptively simple: constrain domestic supply, acquire overseas deposits and producing mines, import large quantities of bullion, build central-bank reserves, and encourage physical ownership beyond the reach of Western futures exchanges. For gold and silver investors, the implication is stark: the world’s largest manufacturing power is positioning for a future in which possession matters more than promises.
Less Mine Supply, More Metal Hunger
China’s domestic raw-gold production fell 14.62% year over year in the first half of 2026, to 152.9 tonnes. Shandong Gold—one of China’s major producers—has also lowered its 2026 mineral-gold output plan from at least 49 tonnes to 36–38 tonnes, potentially a 26.53% reduction. That creates a powerful imbalance: less gold produced at home means more metal must be obtained abroad.
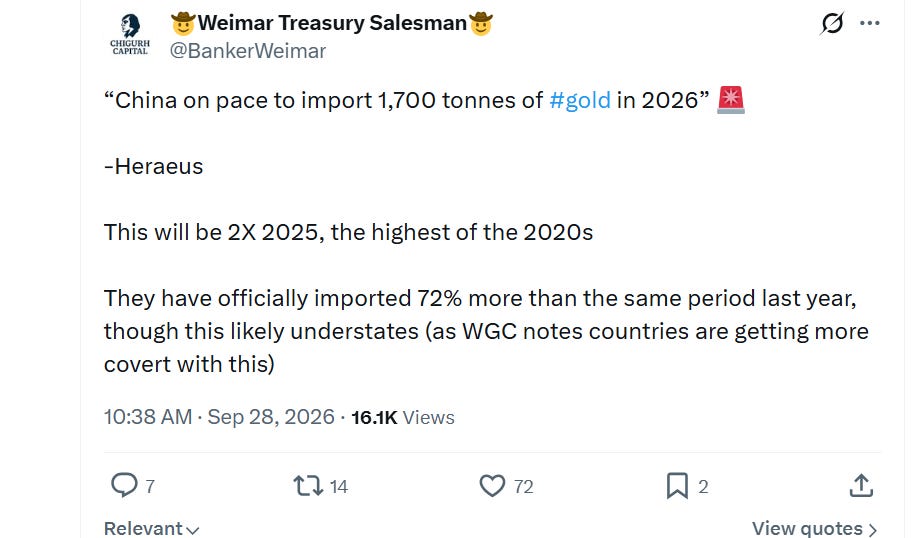
And China is doing exactly that. Through August, the country imported roughly 1,141 tonnes of gold, up 72% from the same period in 2025. Heraeus estimates China could import about 1,700 tonnes in 2026—roughly twice the prior year’s level and the largest total of the decade.
The Central Bank’s Quiet Vote
The People’s Bank of China added 650,000 ounces—20.2 tonnes—of gold in August, its largest monthly purchase since October 2023. It was the 22nd straight month of reported additions, lifting official reserves to about 2,387 tonnes.
Central banks do not accumulate bullion for yield. Gold pays no coupon, carries no counterparty promise, and cannot be created with a keystroke. They accumulate it because it remains final settlement when confidence in sovereign debt, currencies, and financial institutions begins to thin.
Paper Wealth Meets Physical Reality
The United States runs on the opposite model: immense public debt, recurring deficits, and a financial system dependent on ever-expanding credit. Currency debasement is politically easier than fiscal discipline. When foreign buyers become less willing to absorb Treasury issuance, debt must be financed increasingly by domestic institutions—or by policies that suppress interest costs and encourage new money creation.
That is not an automatic hyperinflation forecast. The dollar remains the dominant reserve currency, accounting for 57.13% of disclosed global foreign-exchange reserves in the first quarter of 2026. But reserve diversification, rising gold accumulation, and worsening debt arithmetic reveal a gradual erosion in unquestioned dollar demand.
Diesel: Inflation’s Hidden Fuse
Then comes the energy shock. Diesel is embedded in nearly every physical good: mining equipment, tractors, railroads, trucks, ports, construction machinery, manufacturing, and ocean freight. Recent diesel-price spikes have raised concern that higher transportation and production costs will spread through the wider economy.
The result is a dangerous convergence: more paper claims chasing constrained physical necessities. Gold is monetary insurance against that convergence. Silver may offer greater upside—and volatility—because it is both monetary metal and an irreplaceable industrial input.
The Investor’s Question
The issue is not whether every paper asset collapses tomorrow. The issue is whether investors own enough assets that cannot be printed, defaulted on, or diluted away.
China appears to be answering that question with gold and silver
RE Silver slam yesterday:
Buy the Dip
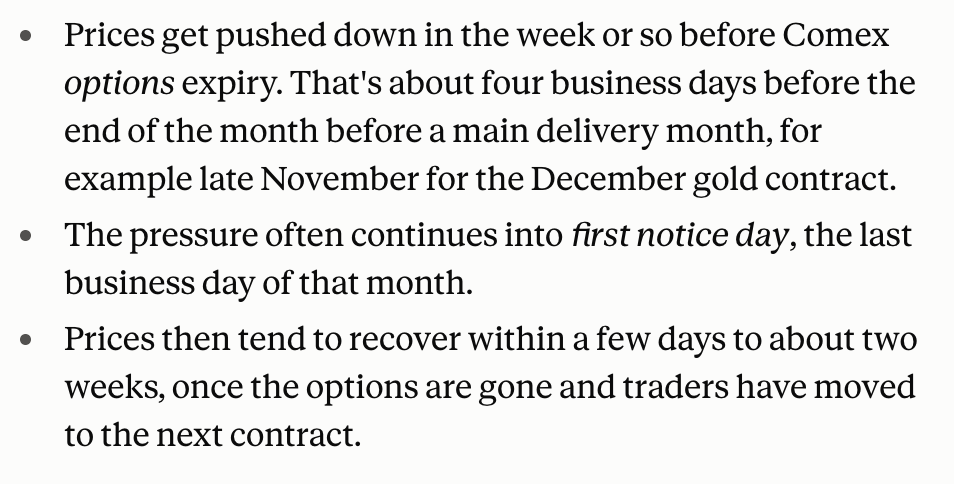
Understand the slam is by design, predictable playbook by Crimex
Stay patient and understand the following
The pressure on gold and silver prices often continues into Comex first notice day, which is Weds 30th Sept.
1. our opinions are not our sponsors opinions
2. the editorial department is separate from the promotions department
3. not financial advice
Disclaimer: Silver Academy is an independent precious-metals content aggregator drawing on analysis, commentary, and research from dozens of third-party writers and market observers. Views, facts, forecasts, and opinions remain those of their respective authors and are not independently guaranteed by Silver Academy. Nothing published constitutes investment, legal, or tax advice. Section 230 protections apply to third-party content; no liability is assumed for investment decisions or third-party statements