The Silver Shock: Why the Window for Sub-$40 Silver Is Slamming Shut
By Jon Forrest Little | Silver Academy
Something historic is unfolding in America’s economic landscape while most investors remain asleep at the wheel. Beneath the mind-numbing headlines about inflation and tech layoffs, a silent stampede is underway—one that could turn the silver market on its head and, for those paying attention, offer one last shot at extraordinary returns.
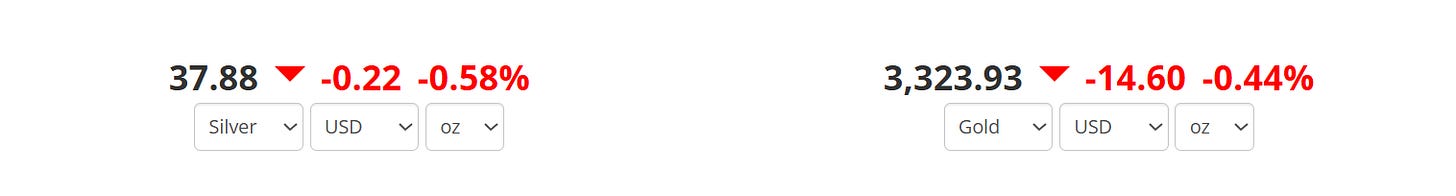
Silver, still trading under $40 per ounce, looks at first glance to be just another rounding error in the hyper-volatile metals sector. Don’t be fooled. Relative to the trillions of dollars in our money supply (M2), silver is not just undervalued—it’s the cheapest it’s ever been in modern history. But it won’t last.
Digital Revolution: From Office Buildings to Data Fortresses
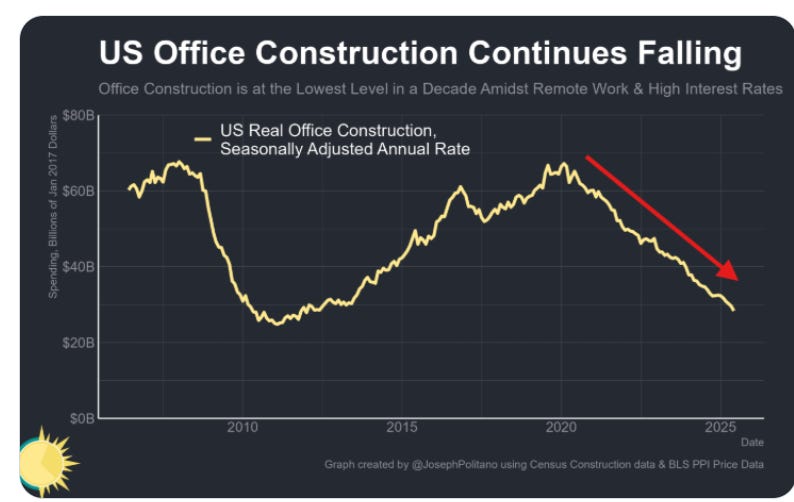
Here’s what’s happening: In a world careening toward total digitalization, America is experiencing the single biggest shift in commercial construction since World War II. Office tower construction, for decades the cathedral of corporate ambition, is crashing. The math is chilling: since 2020, the total value of office buildings under construction has plunged a staggering 50%. Commercial real estate is in crisis, with U.S. office prices down more than 40% from their pre-pandemic highs. Office vacancy rates are nearing 21%—even higher than after the 2008 Financial Crisis.
But where is all the capital fleeing to? Data centers.
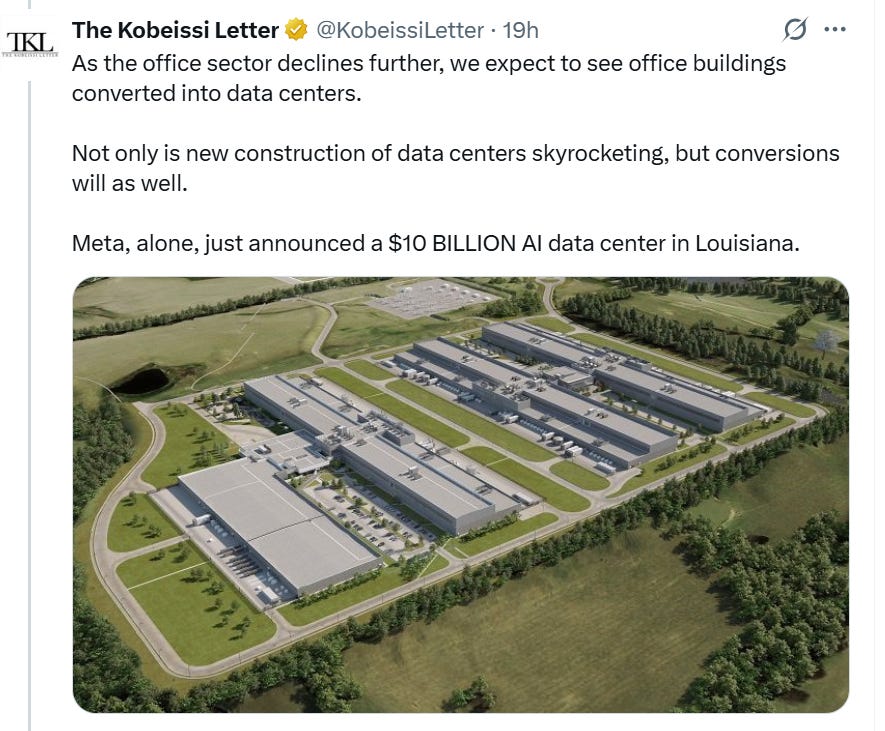
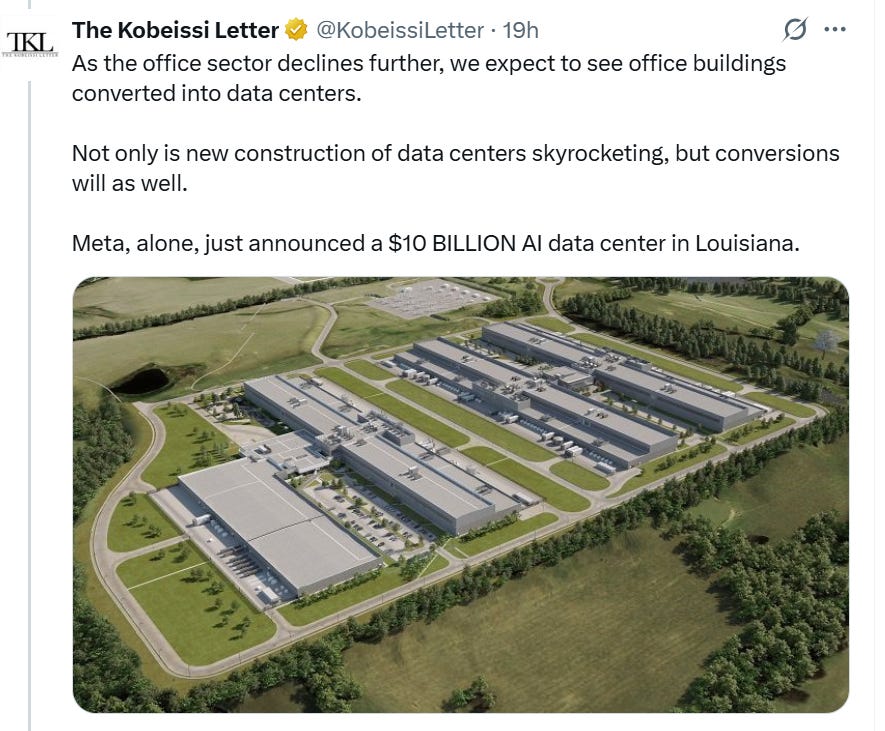
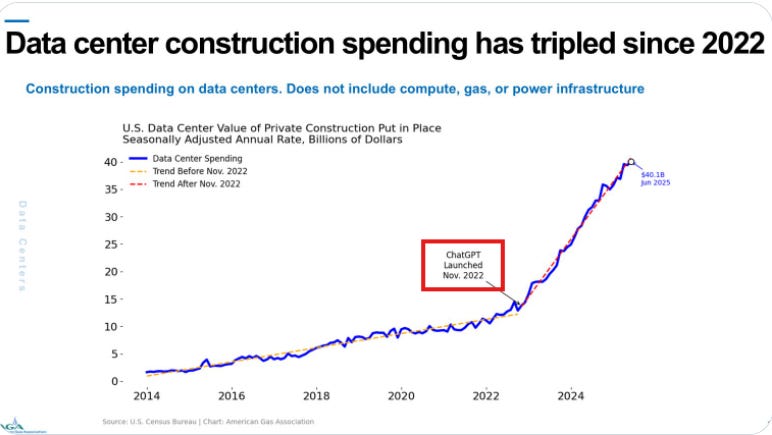
As AI takes command of the world’s workflows, the value of U.S. data centers under construction has rocketed to $40 billion—a jaw-dropping 400% surge since 2022. For the first time ever, America will soon have more value in data centers rising from the ground than office buildings. Meta alone just greenlit a $10 billion AI super-center in Louisiana. This is not some background trend. It’s a tidal wave.
AI: The Real Resource Crunch Is Not Chips—It’s Power
All those hyperscale data fortresses are insatiable beasts. This year, data centers are devouring a record 5% of America’s entire power supply. By 2030, that figure is forecast to more than double. The real AI bottleneck isn’t the number of GPUs you can buy—it’s how much electricity you can generate.
Energy will become the new kingmaker for the AI era. And what’s fueling the new buildout? Solar—powered by silver.
Solar Gold Rush: 700,000 Ounces of Silver per Gigawatt
Here’s the part investors are missing: While Wall Street bets billions on chips, the solar sector is quietly swallowing mountains of silver to keep the AI revolution lit.
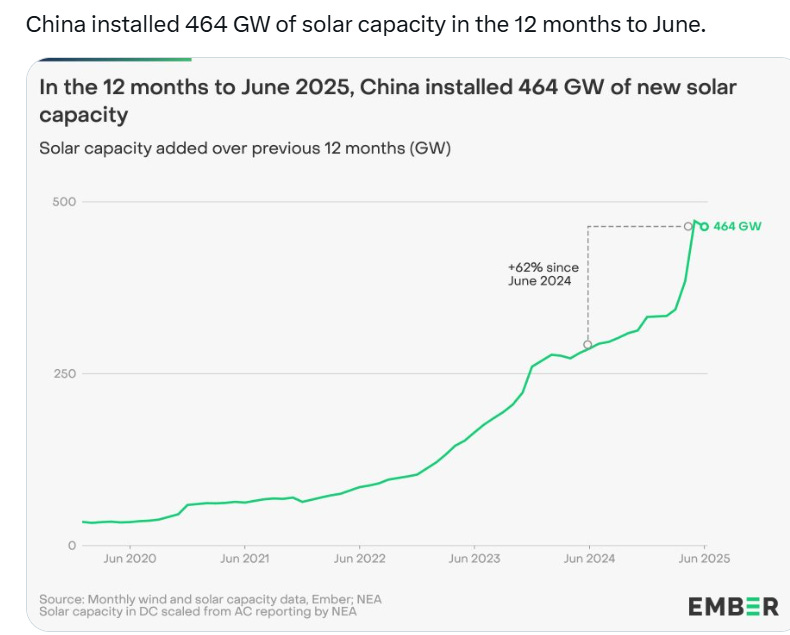
There is currently no substitute for silver’s unique conductivity and reflectivity in solar applications. Each gigawatt of solar capacity consumes around 700,000 ounces of silver. Now, look at what’s happening globally: In just 12 months, China alone installed an unprecedented 464 gigawatts of new solar capacity.
Let’s do the math.
464 GW x 700,000 ounces = 324,800,000 ounces of silver—consumed in a single year by China’s solar expansion alone.
And that’s just one country.
The Supply Crunch: From Dirt Cheap to “Unobtanium”
While demand explodes, silver supply is barely inching upward—and many of the world’s richest silver ores are already depleted. Meanwhile, the “invisible” hand of military demand, now the largest user of silver worldwide, continues to siphon off inventory far from public markets.
Not only is new data center construction set to boom, but so are conversions—repurposing ghost-town offices into AI data fortresses, further stoking energy (and thus, silver) demand. The International Energy Agency projects a 23% compound annual growth rate for data center electricity usage through 2030. Data center loads are on track to account for 40% of all net new power demand for the rest of this decade.
The Urgency: Silver as “Obsoletium” by 2027
The numbers do not lie: We’re witnessing a tectonic shift, both in the macroeconomy and in the very infrastructure that will define the coming decades. Silver—the second largest industrial use being solar, military likely the first—is critical to every leg of this revolution, yet its price languishes, distorted by outdated narratives and paper market games.
But the music will stop—and soon. If global trends continue, silver is on a direct path to becoming unobtainable by 2027. The silver supply/demand equation is flashing a rare, almost blinding bull signal—one that, if history is any guide, will be recognized only in the rearview mirror by most.
When the reckoning comes, the days of $40 silver will be a memory. The opportunity is here, now—but not for long.
The China Factor
Consider this: China’s population eclipses that of the United States by a factor of more than four (roughly 1.4 billion versus 335 million). That scale doesn’t just mean more mouths to feed—it means the country’s drive to overhaul its AI infrastructure and solve its growing energy shortfall operates on another dimension entirely. When China commits to solar, the numbers go stratospheric. At 700,000 ounces of silver per gigawatt of solar, their push to electrify and digitize outpaces the U.S. several times over, draining global silver stockpiles at an unprecedented rate. Not only is their demand set to dwarf America’s, but with China’s Deep Seek AI already outstripping U.S. technologies in critical areas, their hunger for energy—fueled by solar and, by extension, silver—will exert historic pressure on the world’s most undervalued metal. The global market simply cannot match China’s appetite, and once their infrastructure demands hit full stride, silver under $40 may look like a relic of a bygone era.
How to play the AI infrastructure explosion
For investors seeking maximum leverage to the coming silver supply crunch, a handful of miners stand out as the most compelling opportunities—each extremely undervalued and perfectly positioned for explosive growth.
-
Aya Gold & Silver (OTC: AYASF | TSE: AYA) operates Morocco’s renowned Zgounder mine, one of the world’s highest-grade and fastest-growing primary silver projects.
-
Andean Precious Metals (OTC: ANPMF | TSE: APM) runs the San Bartolomé operation in Bolivia, a prolific, low-cost producer sitting atop vast reserves and expansion opportunities.
-
Kuya Silver (OTC: KUYAF | TSE: KUYA) is advancing its flagship Bethania mine in Peru, targeting high-grade silver mineralization in a country synonymous with silver riches.
-
Summa Silver (OTC: SSVRF | TSE: SSVR) just merged with Silver47, creating a junior powerhouse advancing resources totaling nearly 150 million ounces across world-class districts in Nevada, New Mexico, and Alaska.
All four offer unique entry points as silver’s next supercycle begins, providing both near-term production and blue-sky exploration upside.
end of segment
-
our opinions are not our sponsors opinions
-
editorial department is separate from promotions department
-
not financial advice
-
buy the dip