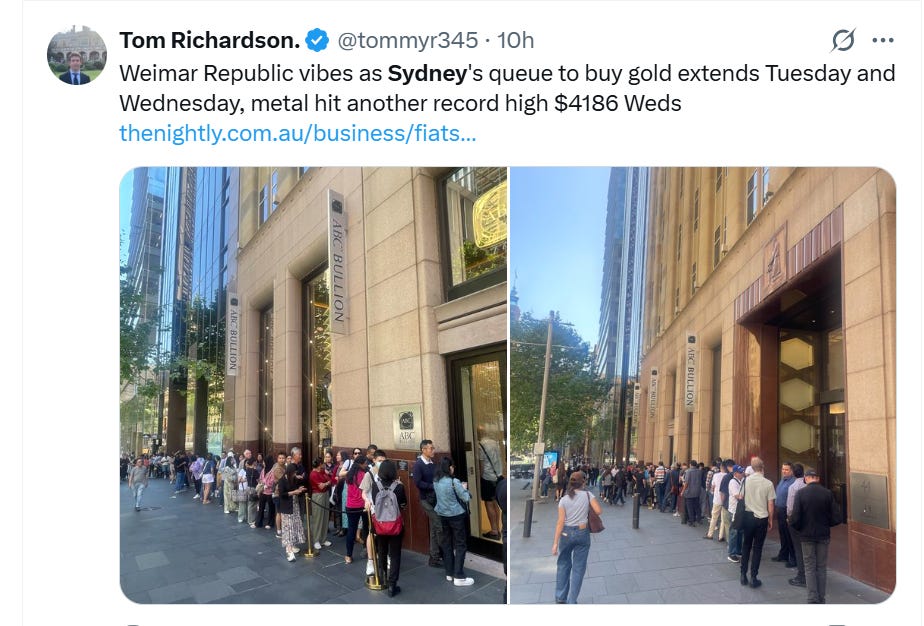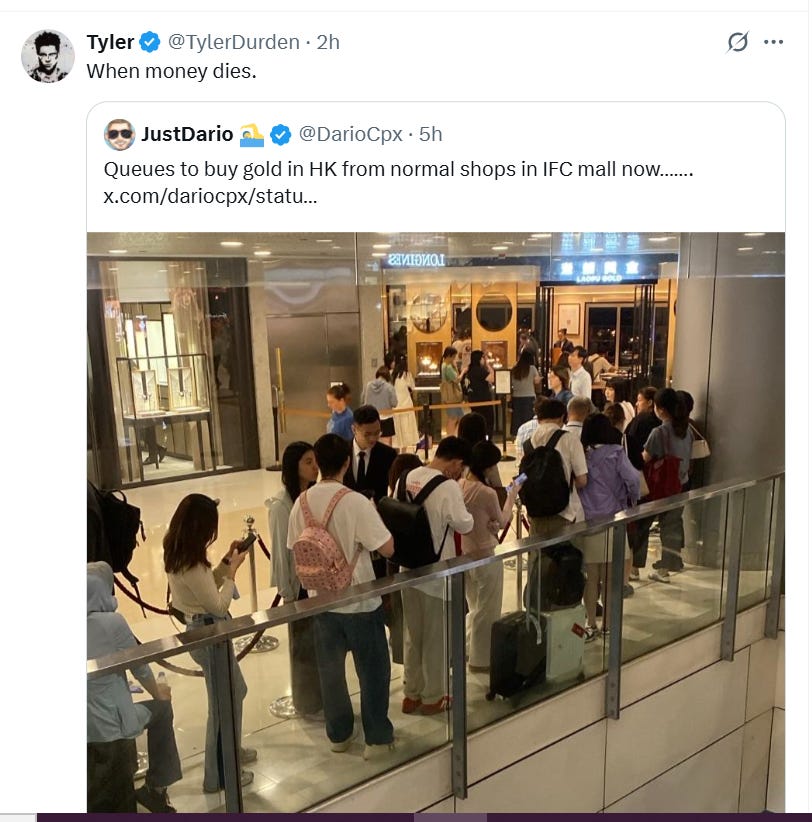
Reports from independent market watchers indicate that the London Bullion Market Association (LBMA) is under severe strain, with insiders describing “panic” as vaults run dangerously low on physical silver. Some commentators claim the LBMA and member banks are urging institutional clients to refrain from new 1,000-ounce bar orders amid extreme shortages, soaring lease rates, and backlogs at refiners. London’s physical silver market remains critically tight, with deliveries reportedly delayed and premiums surging
Let’s see what else is going on around the globe.
The 2025 global silver squeeze has escalated into one of the most dramatic commodities stories in recent memory, reshaping international markets and exposing systemic vulnerabilities across the world’s largest financial hubs. This seismic shift is driven not by speculative hype, but by real, physical demand outpacing available supply, as witnessed in the stampede for physical-backed silver exposures in India and panic-driven rationing in London. The events unfolding this year have transformed the theory of a “silver short squeeze” into undeniable reality, shattering previous records and rewriting the rules for investors, industrial users, and policymakers alike.
India: The Epicenter of Demand
At the heart of this extraordinary development lies India’s SBI Mutual Fund Silver ETF, which has been flooded with record inflows and has delivered near 94% returns over the preceding twelve months—a clear sign that both retail investors and institutions have lost faith in paper silver and are clamoring for physical metal. The phenomenon isn’t confined to a single fund: other Indian silver ETFs have seen explosive growth, only to be forced into temporary suspensions of new share creations as vaults ran dry trying to source sufficient bullion to back soaring demand. Spot premiums for immediate physical delivery in India have risen to a stunning 17% over futures prices, while investors routinely pay more than $200 per kilogram above the global benchmark just to secure silver today.
What makes this moment unique is India’s capacity to import approximately 80% of its silver requirements. For years, the United States held the top spot in silver imports, but 2025 has seen India surpass America, driven by insatiable investment interest and a booming jewelry sector. With Chinese exports tightening, Indian buyers are now locked in fierce competition with London, Canada, Japan, and the USA for dwindling supply—a true race to the bottom in global inventories.
London: Crisis at the Bullion Hub
Meanwhile, the world’s benchmark silver center, the London Bullion Market Association (LBMA), has entered full-blown crisis mode. In a move rarely admitted outside private circles, LBMA executives have reportedly called major customers, pleading with them to suspend or defer purchases of 1,000-ounce 999 fine silver bars. Their aim is simple: to buy time for bullion banks mired in massive, leveraged paper silver positions as they desperately seek to source real metal for industrial giants and sovereign reserves—entities for whom “paper settlement” or delivery delays are not an option.
With lease rates for silver in London surging over 100%—a level signaling panic among market makers—the fragility of the global silver supply chain stands exposed. Manufacturers and national mints that rely on LBMA bars find themselves scrambling for alternatives. Physical premiums are now rising in London too, though not nearly as extreme as in India, providing further evidence that bottlenecks are spreading and delivery certainty is vanishing with each passing week.
The Global Domino Effect
This isn’t merely a two-market drama. The ripple effect is now visible across every major importer:
-
The US, which relies on imports for 81% of its silver consumption, has seen US Mint coin output plummet by 80% this year.
-
The Royal Canadian Mint has suspended large bar production, while Britain’s Royal Mint restricts the ever-popular Britannia series.
-
Andrew Sleigh of SprottMoney.com states, “I have never seen Royal Canadian mint sell out of 100 ounce silver bars, ever”
-
South Africa’s Rand Refinery, a stalwart of the investment coin industry, halted silver Krugerrands.
-
Premiums from North American to European dealers continue to rise, reflecting the reality that paper promises cannot substitute for physical bars or coins.
All signals point to a synchronous global squeeze. With industrial demand steady or rising and central banks not selling, the available float of deliverable silver has fallen to multi-decade lows. The entire market now confronts a harsh truth: when the largest importers and mints cannot get metal—even at sharply higher prices—the underlying paper pricing mechanism is fundamentally broken.
Silver Price Explosion and Existential Shift
Against this backdrop, silver prices have rocketed past $52/ounce in 2025, setting new all-time highs and positioning the metal as the best-performing major asset of the year—handily outperforming gold’s much-heralded rally. For investors, the lesson is clear: only physical silver offers certainty in a time of systemic stress. For mints, manufacturers, and sovereign reserves, the distinction between “paper” silver and “real” metal has never been more consequential.
The Future: Physical Silver is Essential
The great silver short squeeze of 2025 has moved from theory to front-page fact. India’s surging ETF demand and London’s market turmoil reveal a simple, unvarnished new reality for the global financial system: physical silver is no longer a luxury or speculative play—it is existential. The world’s largest paper market has been reduced to crisis calls, industrial buyers are forced to scramble, and investors everywhere are recalibrating portfolios for the age of real, tangible assets.
This is the dawn of a new era for silver, where scarcity rules and possession is not just nine-tenths of the law—it is the only law that matters.