
THE GREAT SILVER FLIGHT: 2026 AND THE END OF THE PAPER AGE
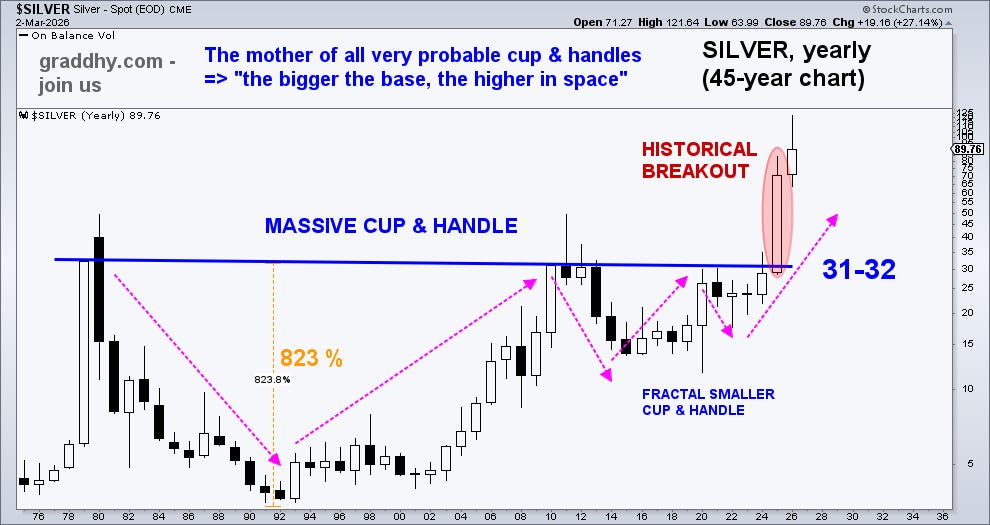
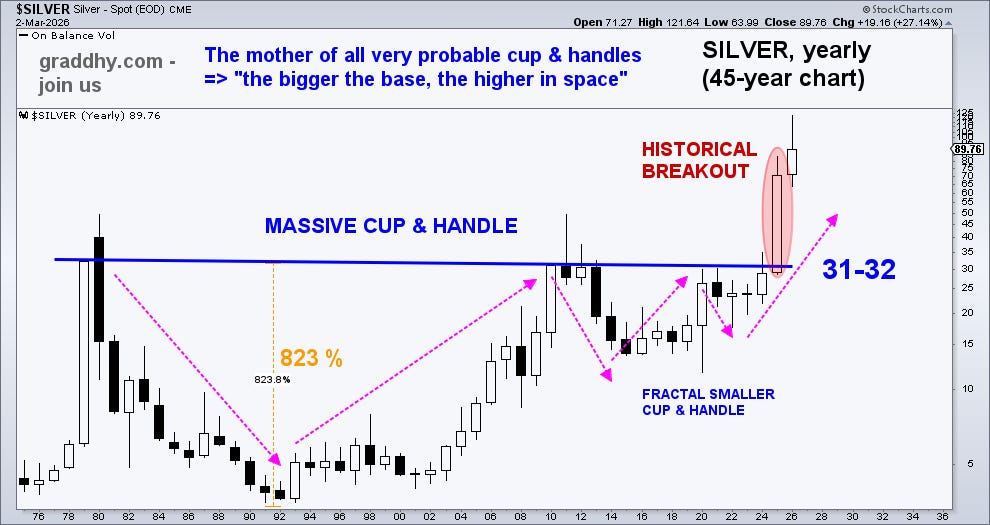
In 2024, the breakout was close. Through 2025, the setup only grew louder: supply tightening, premiums rising, and physical silver draining quietly from Western vaults. The $30–32 range wasn’t the finish line—it was the ignition point. When the breakout came, $70 was no longer a dream. It was a milestone on the way to $121.
Now, in 2026, the Great Silver Flight has arrived.
While Western traders still gamble with paper contracts on the COMEX, the real action is half a world away. The East isn’t trading; it’s taking. Physical silver is leaving the West in a steady, unstoppable flow—and with it, the illusion of abundance.
1. The Inventory Collapse
COMEX registered silver inventories have imploded to just 88 million ounces—down a staggering 75% from 2020 levels. Open interest, representing paper “claims,” sits near 230 million ounces. That’s nearly three ounces promised for every real one. The exit door is narrowing fast, and when all claimants rush at once, there won’t be enough metal to go around.
2. The Asia Premium
The disconnect between paper and physical markets has widened into a canyon. Shanghai’s silver premium recently hit a jaw-dropping $10 per ounce over London and New York prices. In February alone, India imported roughly $1.75 billion worth of silver—an estimated 76 million ounces in 28 days. That’s not a market; that’s a vacuum sucking physical supply eastward.
Physical is no longer just scarce—it’s strategic.
3. The Price Divergence
While COMEX shorts—often the same institutions that sponsor the exchange—fight to suppress prices, local markets are breaking free. In India, silver just hit a record ₹3,15,100 per kilogram, reflecting real-world scarcity rather than digital positioning. The battle between derivative suppression and physical demand is entering its final act, and the victor will be tangible metal, not leverage.
4. The Corporate Signal
Follow the capital, not the commentary. BHP Group just secured a $4.3 billion silver supply deal to lock in access years ahead. That’s not speculation—it’s survival strategy. With six straight years of global supply deficits, even industrial giants now see silver for what it is: a resource moving from cheap commodity to critical asset.
5. The Turning Point
The West may own the paper, but the East owns the metal. And when the paper squeeze reaches its breaking point, price discovery won’t happen on a trading screen—it’ll happen at the vault door.
Silver’s revaluation has only begun. The structural shortfall, industrial demand, and monetary awakening are converging. My long‑term outlook remains $370, with potential for a late‑cycle mania spike above $500.
The age of paper silver is ending. Physical possession, not promises, will define the next phase. The world is witnessing the Great Silver Flight—and it’s already airborne.
Buy these Dips
Miners poised to explode to the upside.
Aya Gold & Silver (TSX: AYA, OTC: AYASF), Andean Precious Metals (TSX-V: APM, OTC: ANPMF), and Kuya Silver (CSE: KUYA, OTC: KUYAF) are where you buy the pain for future torque. These are primary silver vehicles, not base‑metal mines tossing you a few silver crumbs. Aya is guiding strong AgEq growth from Zgounder and remains one of the cleanest pure-play silver growth stories on the market, with cash flow tied directly to the silver price, not by-product credits.
Andean controls San Bartolomé plus Golden Queen, with tens of millions of silver ounces in the resource base and a business model built around monetizing silver, not hiding it behind copper or zinc.
Kuya is rebuilding a high‑grade primary silver footprint at Bethania and Silver Kings, targeting silver production with ultra-low capex and aggressive drilling as the silver cycle turns.
end of segment
-
our opinions are not our sponsors opinions
-
the editorial department is separate from the promotions department
-
not financial advice