
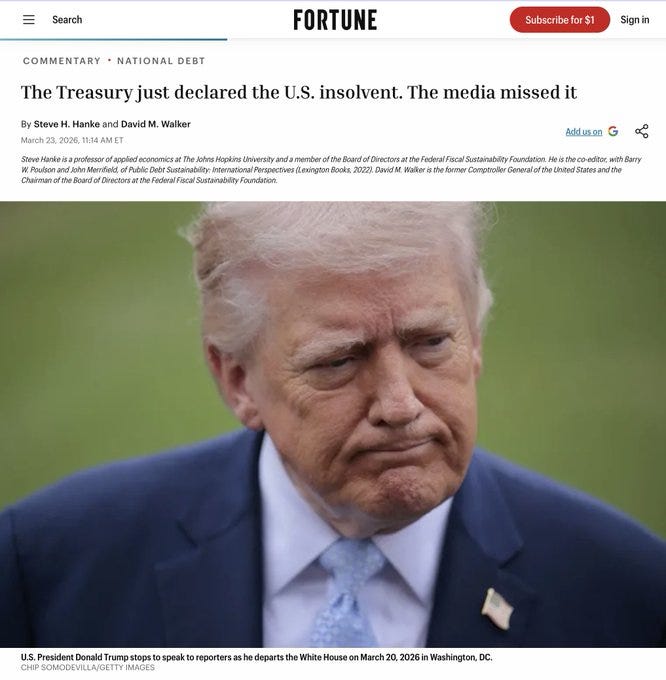
Washington launched an illegal and immoral war on Iran to stop a nuclear program that its own former counterterror chief says did not exist—while the Treasury’s books quietly confirm something equally as terrifying: it’s America, not Iran, that is bankrupt.
This is what empire in decline looks like: bombing a country that was still participating in negotiations under a deal Donald Trump shredded, even as the U.S. balance sheet collapses, housing craters, and the biggest oil shock in modern history detonates under the real economy.
A war built on a lie
Joe Kent, who just resigned as Trump’s counterterrorism chief, is on record saying Tehran was “nowhere close” to a nuclear weapon and that the official U.S. intel assessment said the same. He has also blasted the administration’s “imminent threat” narrative, making clear that the White House’s public claims about Iran’s nuclear danger directly contradicted what the intelligence community was actually reporting.
Remember: Iran had been bound by the Joint Comprehensive Plan of Action (JCPOA), the multilateral nuclear deal Trump unilaterally tore up in 2018 over the objections of U.S. allies, even though it was explicitly designed to keep Iran from getting a bomb. To start this war now, under the banner of a nuclear menace that the administration’s own former top counterterror official says did not exist, isn’t just reckless; it is a textbook case of an aggressive war of choice—a crime under the standards we once imposed on others
Bombs abroad, bankruptcy at home
While cable news gorged itself on breathless “epic fury” B‑roll from the Persian Gulf, the Treasury Department quietly released its consolidated financial statements for FY 2025. Buried in those dry tables is a political IED: the U.S. government lists just over $6.06 trillion in assets against roughly $47.78 trillion in total liabilities as of September 30, 2025. In plainer English, Hanke and Walker conclude in Fortune that the United States government is insolvent, with liabilities nearly eight times reported assets and a negative net position of about $41.72 trillion that deteriorated by more than $2 trillion in a single year.
Yet the same political class presiding over this fiscal train wreck has somehow found the money for another elective Middle East war. Interest-bearing debt and veterans’ and federal employee benefits—obligations to past wars and past promises—are now among the fastest-growing liabilities on the federal books. A bankrupt empire that cannot maintain its own balance sheet is lighting billions on fire in a war its own former security chiefs say was sold on false pretenses.
Housing collapse and oil shock
The damage is not abstract. Existing‑home sales in January 2026 sank to an annual pace of about 3.91 million, down 8.4% from the prior month and 4.4% from a year earlier, the worst start to a year since the depths of the last housing slump. Inventory has been grinding lower, leaving would‑be buyers facing a toxic brew of high prices, scarce listings, and rising economic uncertainty as war‑driven energy and financing costs ripple through the system. This is what a controlled burn of the middle class looks like: a generation locked out of homeownership while Washington blows up Iranian infrastructure and pretends that’s “strength.”
At the same time, the Iran war has triggered the largest oil supply shock on record. With tanker traffic through the Strait of Hormuz choked off and regional producers slashing output, roughly 20% of global oil supply has been disrupted—far surpassing the 1973 embargo or the Iranian Revolution, according to recent industry and IEA assessments. Saudi Aramco’s leadership is warning of “catastrophic” consequences as onshore storage fills and exports stall, a scenario that historically shaves 1–3 percentage points off global growth and turbocharges inflation across Europe and Asia.
This is the real obscenity: an administration that lied the country into an Iran war while its own Treasury data show the government is functionally insolvent; that pulverized a functioning nuclear agreement, then used its absence as a pretext for bombardment; that presides over a housing crash and the biggest oil shock in history—then dares to wrap it all in the flag and call it “epic fury.”
-
Minutes before Trump’s “peace in our time” Iran speech, someone magically knows what’s coming.
-
Roughly $1.5 billion in S&P (ES) futures hoovered up, $192 million in oil (CL) futures puked out—4–6x the size of anything else on the tape.
-
Market goes exactly where it “should,” and our mystery genius prints a fortune. Total coincidence, obviously.
-
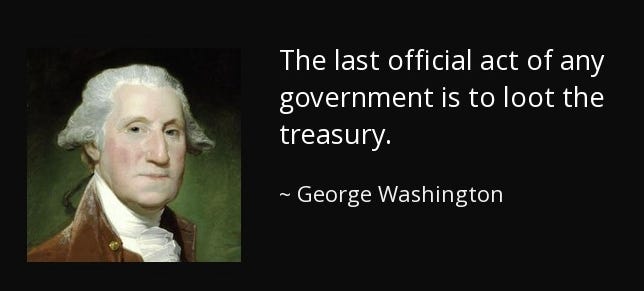
Meanwhile, the country behind this casino: $47 trillion in total liabilities, $6 trillion in total assets. Insolvent, but very patriotic.
-
Forever wars are now mathematically non‑financiable… unless you’re front‑running the ceasefire.
-
Trump allegedly stares at the bond market, panics, and dials down his “ultimatum.”
-
On the way out, the gangster circle skims the pot one more time. Democracy, but make it organized crime.
our opinions are not our sponsors opinions, the editorial department is separate from the promotions department, not financial advice