
-
Silver miners are about to enter a violent revaluation as their spread against gold keeps breaks higher
-
Confirming capital is rotating toward miners.
-
That breakout would signal more than prices: it would announce a valuation regime where ignored earnings and margins demand recognition.
-
Silver’s catch-up move can magnify increases in realized metal prices, while many production costs remain fixed, sending profitability sharply upward.
-
The market rarely rewards miners gradually once momentum turns.
-
Latecomers chase headlines, scarcity narratives, and exceptional results, intensifying the rerating.
-
This is not a sector rally. It is “fasten your seatbelt time”
-
A rapid scramble for undervalued companies before the crowd understands.
-
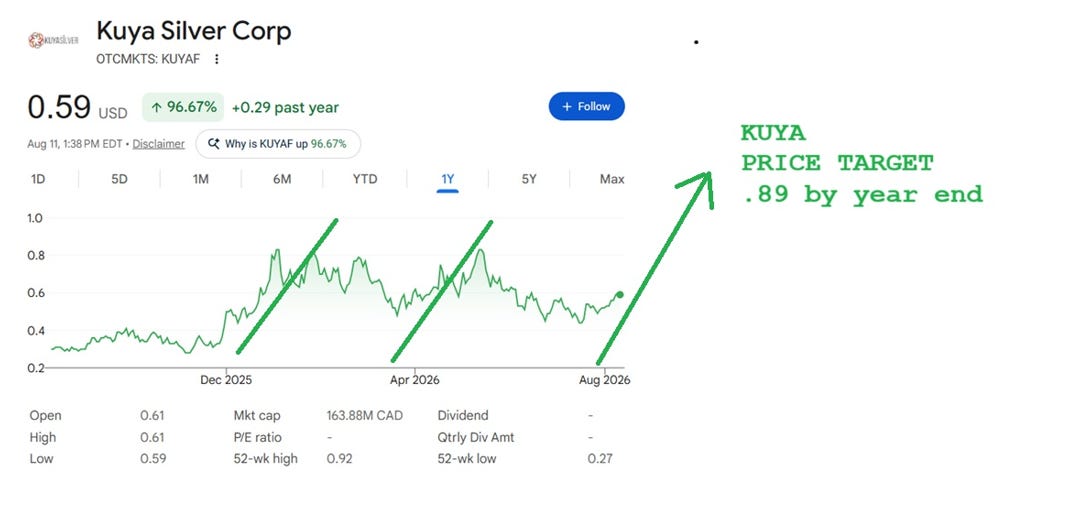
Kuya Silver offers unusually direct leverage to silver because Bethania’s economics are dominated by the metal investors want exposure to silver.
-
The mine is now moving through its operational ramp-up, where rising throughput can transform a previously underappreciated asset into a visible growth story.
-
Each operational milestone can sharpen market attention on production, grades, and cash flow.
-
Bethania delivered a record Q2: 5,097 tonnes of mineralized material mined, a 66% quarter-over-quarter increase as its production ramp-up accelerated.
-
The mine processed a record 23,912 ounces of silver, or 30,559 silver-equivalent ounces, showing progress from development into increasing production.
-
June established operating benchmarks: 2,040 tonnes mined, averaging 68 tonnes daily, and a record 13,273 silver-equivalent ounces produced that month.
-
Daily production reached a record 124 tonnes, while June silver grades climbed to 6.66 ounces per tonne, above management’s expectations.
-
Underground development reached 437 metres; a dual-car hoisting system, expected in October, is to improve ore-extraction efficiency and expand capacity
All of this makes Kuya a compelling silver-led rerating candidate, as ramp-up execution continues.
and now understand the greater context of the misunderstood Silver market.
Silver’s Great Mispricing
Silver is not merely cheap; it is profoundly mispriced against the monetary and industrial realities now converging around it. For years, investors have treated silver as gold’s volatile little brother—useful in rallies, disposable in corrections. That complacency is precisely the opportunity. Silver has endured supply deficits, rising industrial demand, and a period of relative undervaluation versus gold and the broader metals complex. Yet price has refused to reflect that pressure. Markets can ignore a distortion for years. They cannot ignore it forever. When a compressed market finally breaks free, the move is rarely polite. It is abrupt, violent, unforgiving.
The Metal That Never Caught Up
Consider the scale of the anomaly. Many commodities and metals trade multiples above their 1980 levels, while silver has spent decades struggling around its nominal ceiling. Gold has reasserted itself as a monetary reserve asset; silver remains a monetary metal with history and an indispensable industrial input. It is used in electrification, solar technology, electronics, applications, and manufacturing. Unlike paper currency, it cannot be printed. Unlike financial assets, it cannot be created instantly. The market is finite, supply is constrained, and much production arrives from other mining. Rising demand meets a supply response that is slow, costly, and structurally limited.
When Paper Promises Break
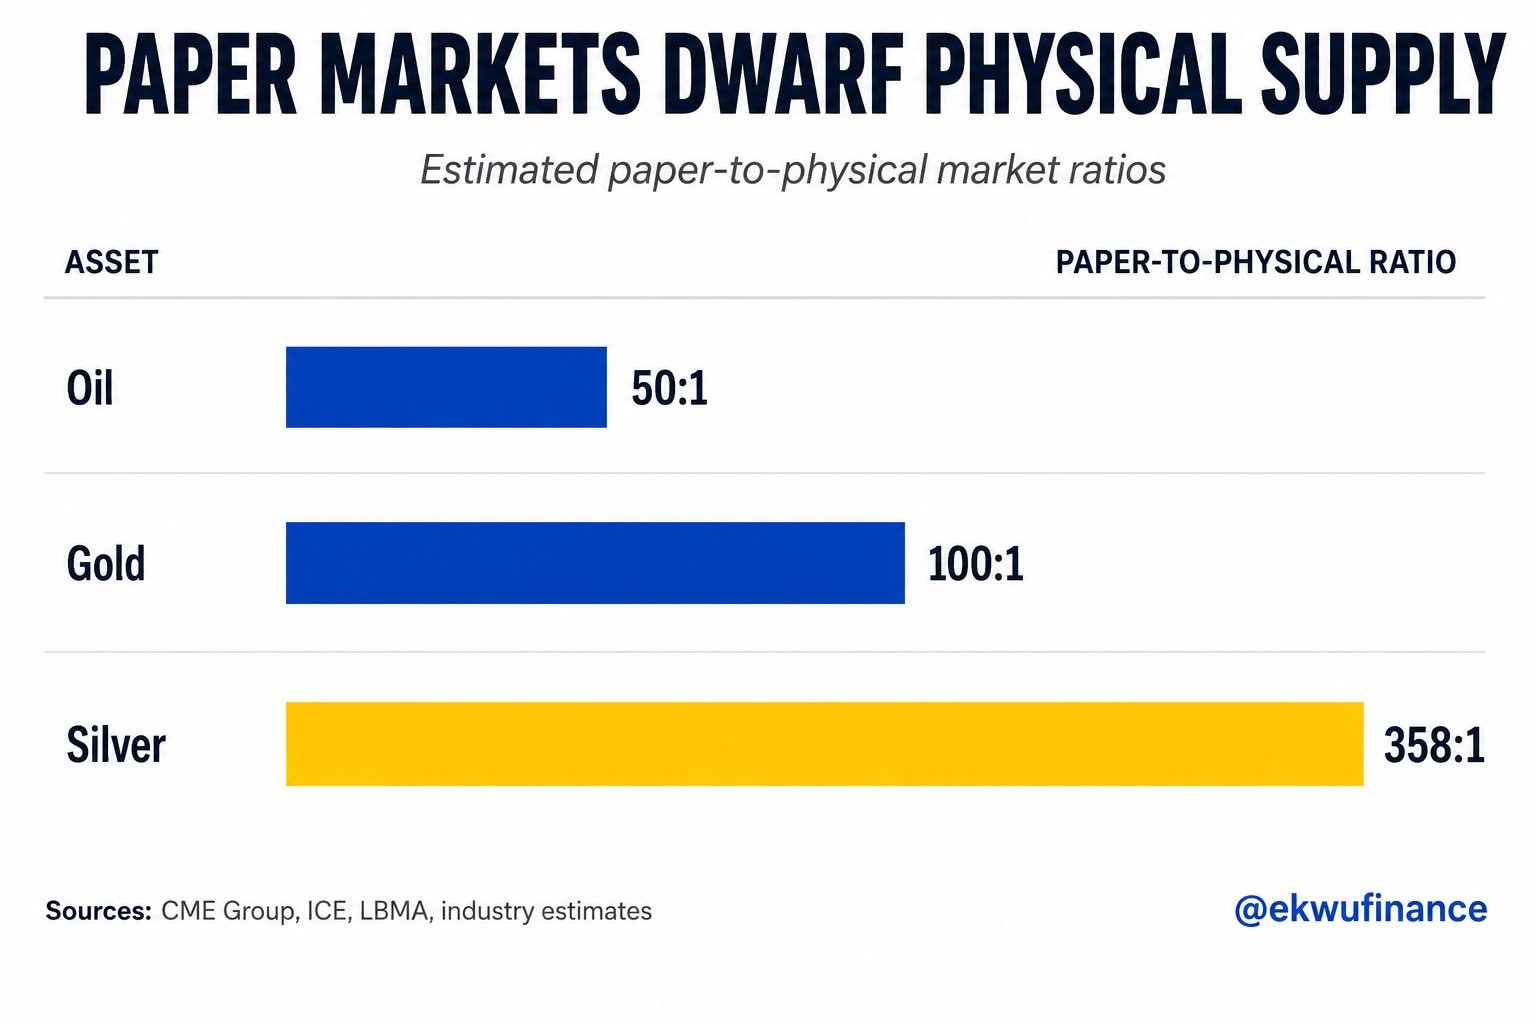
Paper markets dwarf physical supply.
– Oil: 50:1
– Gold: 100:1
– Silver: 358:1
By flooding the market with paper contracts, you can trigger huge price swings… especially during thinly traded hours. – Ekwufinance
The catalyst is not a headline. It is the collision of debt, currency debasement, physical availability, and recognition that traditional portfolios are exposed to sovereign bonds and inflated equities. Governments facing unpayable obligations cannot solve it through austerity; they lean on money expansion and policies that erode purchasing power. That is the environment in which monetary metals stop being “alternative” assets and become insurance. Gold has already signaled the shift. Silver is the coiled spring: smaller, less liquid, and therefore capable of moving far faster when capital begins chasing limited ounces. An allocation wave can become a stampede.
The Coiled Spring Snaps
This is why silver’s next advance may not resemble a bull market. The public buys late, when prices validate the story, headlines turn euphoric, and fear of missing out overwhelms prudence. By then, metal may be scarce, premiums elevated, and quality mining equities repriced. Silver miners offer leverage to a rising silver price because prices can expand margins once costs are covered. Leverage cuts both ways. The point is simple: silver’s consolidation has built energy, not erased value. When the market accepts the reality visible in supply, demand, and conditions, today’s “expensive” price may still look absurdly cheap.
our opinions are not our sponsors opinions
the editorial department is separate from the promotions department
not financial advice