
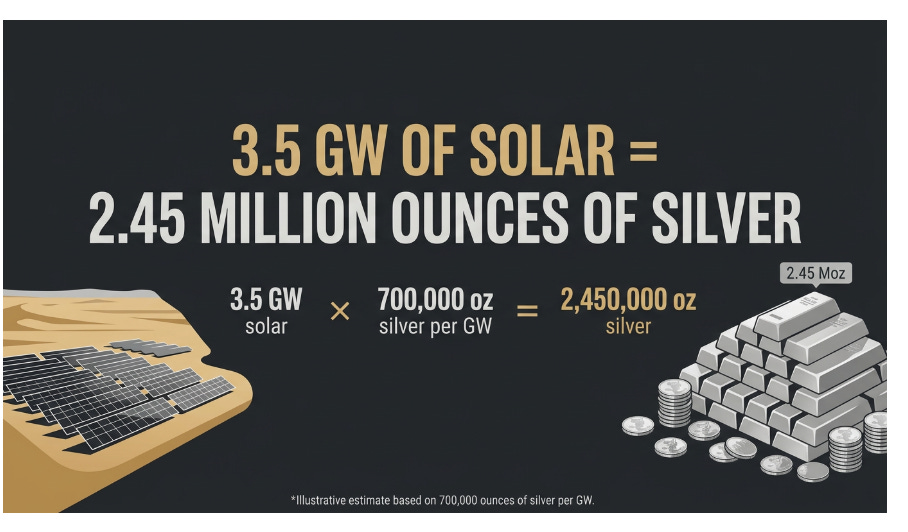
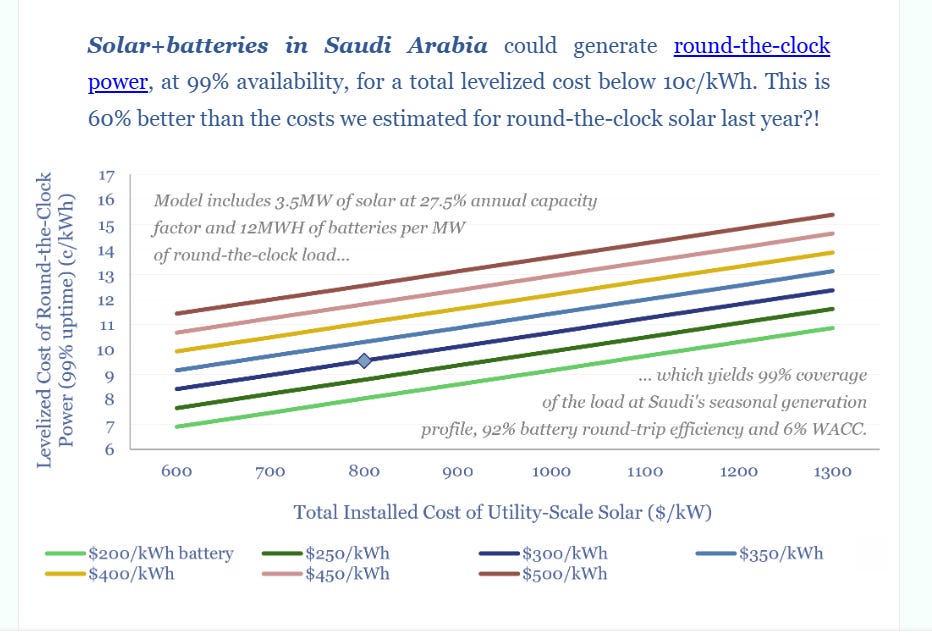
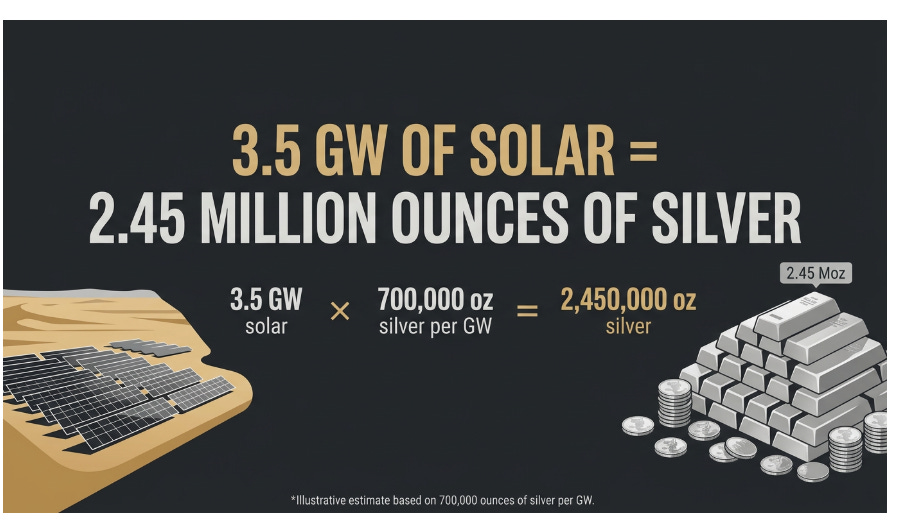
Saudi Arabia’s solar-and-battery opportunity is more than a clean-energy story—it is a strategic resilience story. New analysis suggests that round-the-clock electricity could be delivered at roughly 10 cents per kWh, using only 3.5 MW of solar capacity per MW of constant demand, rather than the far more extreme oversizing required in less favorable solar regions. For a 1 GW data center, that implies about 3.5 GW of solar and 12 GWh of batteries—an enormous project, but one that would occupy only a tiny fraction of the Arabian Desert.
The recent Iran conflict and the risk of disruptions around the Strait of Hormuz may have underscored a basic vulnerability: even the world’s premier oil producer depends on exposed fields, export routes, processing infrastructure, and shipping chokepoints. Distributed domestic solar, storage, and power-hungry industries can reduce reliance on vulnerable fuel logistics while preserving more hydrocarbons for export. It is an energy-security hedge as much as an energy transition.
-
Silver is entering its sixth consecutive annual market deficit, with global demand expected to exceed total supply again in 2026. The important point is not merely one year’s shortfall, but a multi-year drawdown in above-ground inventories while industrial demand remains structurally elevated.
-
Annual mine production is roughly 820 million ounces, while total silver use has been cited near 1.3 billion ounces when industrial fabrication, investment, jewelry, silverware, and other demand are included. The gap must be met from recycling and existing inventories—and those inventories are finite.
-
Virtually every major growth industry is becoming more electricity-intensive. Silver remains the most electrically conductive metal, embedding it in solar panels, AI and data-center hardware, robotics, aerospace, military electronics, EVs, transportation systems, batteries, and grid infrastructure.
-
Supply cannot quickly respond: roughly 70% of mined silver is produced as a by-product of lead, zinc, copper, and gold mining. Higher silver prices alone therefore may not create enough new output.
-
China reportedly processes about 60–70% of globally traded refined silver and has tightened export rules, adding a geopolitical bottleneck to an already constrained market.
-
Monetary demand could become the second pressure point. A falling gold-to-silver ratio toward historical norms—and renewed sovereign or investor accumulation—would collide directly with industrial demand.
-
The defining question is simple: where will the incremental silver come from?
Against this tightening silver backdrop, Aya Gold & Silver (AYA) offers a potential supply-side bright spot. Its Boumadine Preliminary Economic Assessment (PEA) and updated Mineral Resource Estimate (MRE) outline a large, capital-efficient Moroccan project with 81.2 million ounces of life-of-mine physical silver production—16% higher than before—alongside substantial gold-equivalent output and expansion upside.
Boumadine breaks ground Q1 2027, ahead of schedule
Please see the updated Boumadine PEA and MRE, completed with SRK and Lycopodium.
SRK Consulting is the independent mining consultancy updating Boumadine’s Mineral Resource Estimate. Lycopodium is the engineering firm responsible for process-plant design, flowsheet optimization, equipment sizing, and feasibility-level cost estimates.
The headline: Boumadine has emerged as one of the most capital-efficient large scale precious metals projects in the sector. Strong economics, payabilities, and lots of optionality beyond the base case.
-
Base case: $3.5B NPV5%, 93% IRR, 0.7-year payback and $4.7B LOM FCF
-
Spot: $5.5B NPV5%, 128% IRR and $7.3B LOM FCF
-
Initial capex of $463M — NPV/Capex of 7.6x base case and 11.9x at spot
-
Production of ~348 koz/yr AuEq in Years 1–5 at ~$1,105/oz AISC
-
Updated MRE: ~5.4 Moz AuEq (M&I + Inferred) at ~3.1 g/t AuEq (~501 Moz AgEq at ~300 g/t AgEq) with ~500Koz AuEq excluded – to be converted with more drilling
-
81.2 Moz LOM physical silver production, up 16% — as much as Zgounder today
Base case of 8,000 tpd → 348 koz AuEq/yr to be scaled up with FS in H2 2027 contemplating +10 Ktpd, backed by additional high impact/ adjacent permits and 400 km of drilling across our ~939 km² land package (339 km² granted + 600 km² under exploration authorization).
Breaking ground Q1 2027. Self-funded, with access to external debt. Production by 2030 – half the time from discovery to production at 5 years vs. the industry average
Strong economics today. A bigger project tomorrow.
end of segment
our opinions are not our sponsors opinions
the editorial department is separate from the promotions department
not financial advice